
Uk Plans To Eliminate Contactless Payment Limits Sparking Fraud Concerns
Okay, picture this. You’re at a bustling coffee shop, late for a meeting. You tap your card on the reader, grab your latte, and sprint out the door. No PIN, no signature, just a beep and a blessing.
Now imagine that same tap, but for a £300 jacket, or a £500 grocery run. Sounds convenient, right? Or does it sound like a nightmare waiting to happen?
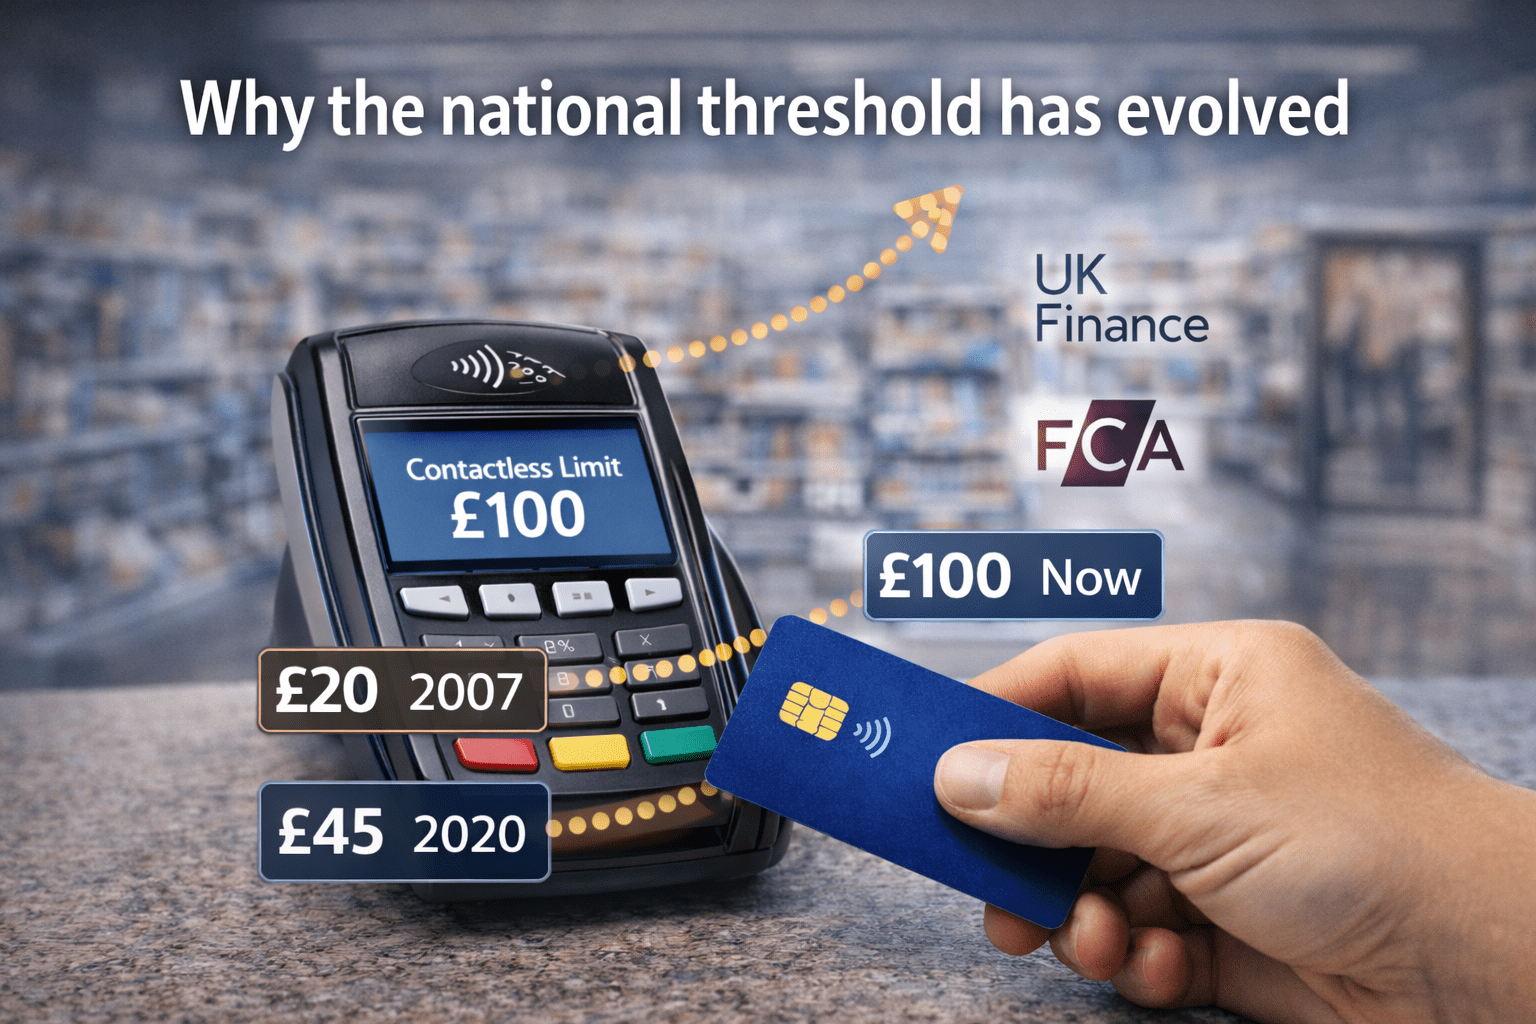
The UK government is currently exploring plans to scrap the contactless payment limit entirely. Yes, that friendly little £100 ceiling might be history. And while the idea screams “efficiency,” a lot of people are screaming “fraud risk.”
Must Read
- Did Kelly Clarkson Just Get Julia Roberts Treatment? The Untold Truth Behind Brooklyn’s $15m Animatronic Bird Drama
- The 5-minute Visit That Broke The Internet: How Kelly Clarkson Sparked A $15 Million Mechanical Bird War
- Petty Revenge Or Viral Genius? Brooklyn Store Slaps $15,000,000 Tag On Molly The Bird After Kelly Clarkson Backlash
Let’s be real—we love convenience. Who hasn’t tapped their phone to buy a round of drinks without fumbling for cash? But here’s the twist: removing the cap could turn your card into an open wallet for anyone with a scanner.
Think about it. If there’s no limit, a thief who snatches your card could theoretically buy a new TV, a plane ticket, and a lifetime supply of avocados in one smooth tap. No pin, no password, no problem—for them.
How did we get here? The tap-and-go revolution
Remember when contactless payments were a novelty? You’d tap for a £5 sandwich and feel like a wizard. Now it’s the norm, and the UK wants to level up.
The argument from the government is that removing limits boosts the economy. Faster checkouts, less queuing, more spending. Businesses love it because it reduces cash handling and speeds up transactions.
But here’s the thing—fraud is already a beast. In 2023, contactless fraud in the UK hit record levels, with criminals using stolen cards for small, untraceable taps. Remove the limit, and you hand them a crowbar.
The scary part: What happens when your card goes missing?
Imagine you lose your wallet during a commute. With a £100 limit, the thief can buy a nice dinner and some petrol before the card is blocked. Annoying, but manageable.
Now imagine no limit. That same thief could drain your account in one trip to the shops. You might not even notice until your bank statement screams “new sofa.” And by then, the damage is done.
Banks say they’ll protect you with fraud guarantees, but those take time. Meanwhile, you’re dealing with paperwork, stress, and possibly a temporary overdraft. Fun, right?
There’s also the issue of “shoulder surfing”—someone peeking at your card details while you tap. With a limit, it’s annoying. Without one, it’s a goldmine for criminals.
What about digital wallets? Apple Pay, Google Pay, and the NFC loophole
Here’s where it gets ironic. Digital wallets like Apple Pay already allow unlimited transactions because they use biometrics (your face or finger). So the physical card is the weak link.
The government’s plan would essentially make physical cards behave like digital ones. But here’s the catch: digital wallets require you to unlock your phone. A stolen card? No unlock needed.
So why push this? Critics argue it’s a lobbying victory for big retailers who want frictionless spending. But for the average person, it feels like being asked to leave your front door unlocked in a dodgy neighborhood.
What security experts are saying (spoiler: they’re nervous)
I spoke to a fraud analyst friend (names withheld, you know the drill). He said, “Removing the limit is like handing a toddler a credit card and hoping they don’t buy a pony.” Ouch.
He pointed out that fraudsters are already testing NFC readers in crowds. With no limit, they could “tap” your card from your pocket using a hidden scanner. Yes, that’s a real thing—it’s called relay fraud.
Banks have some safeguards, like requiring a PIN after a few taps. But if the limit goes, those safeguards become meaningless. One tap, one disaster.
But wait—could this actually be safer?
Okay, let’s play devil’s advocate. Some argue that removing limits reduces fraud because criminals won’t bother with small amounts. Wrong. They’ll just target bigger prizes.
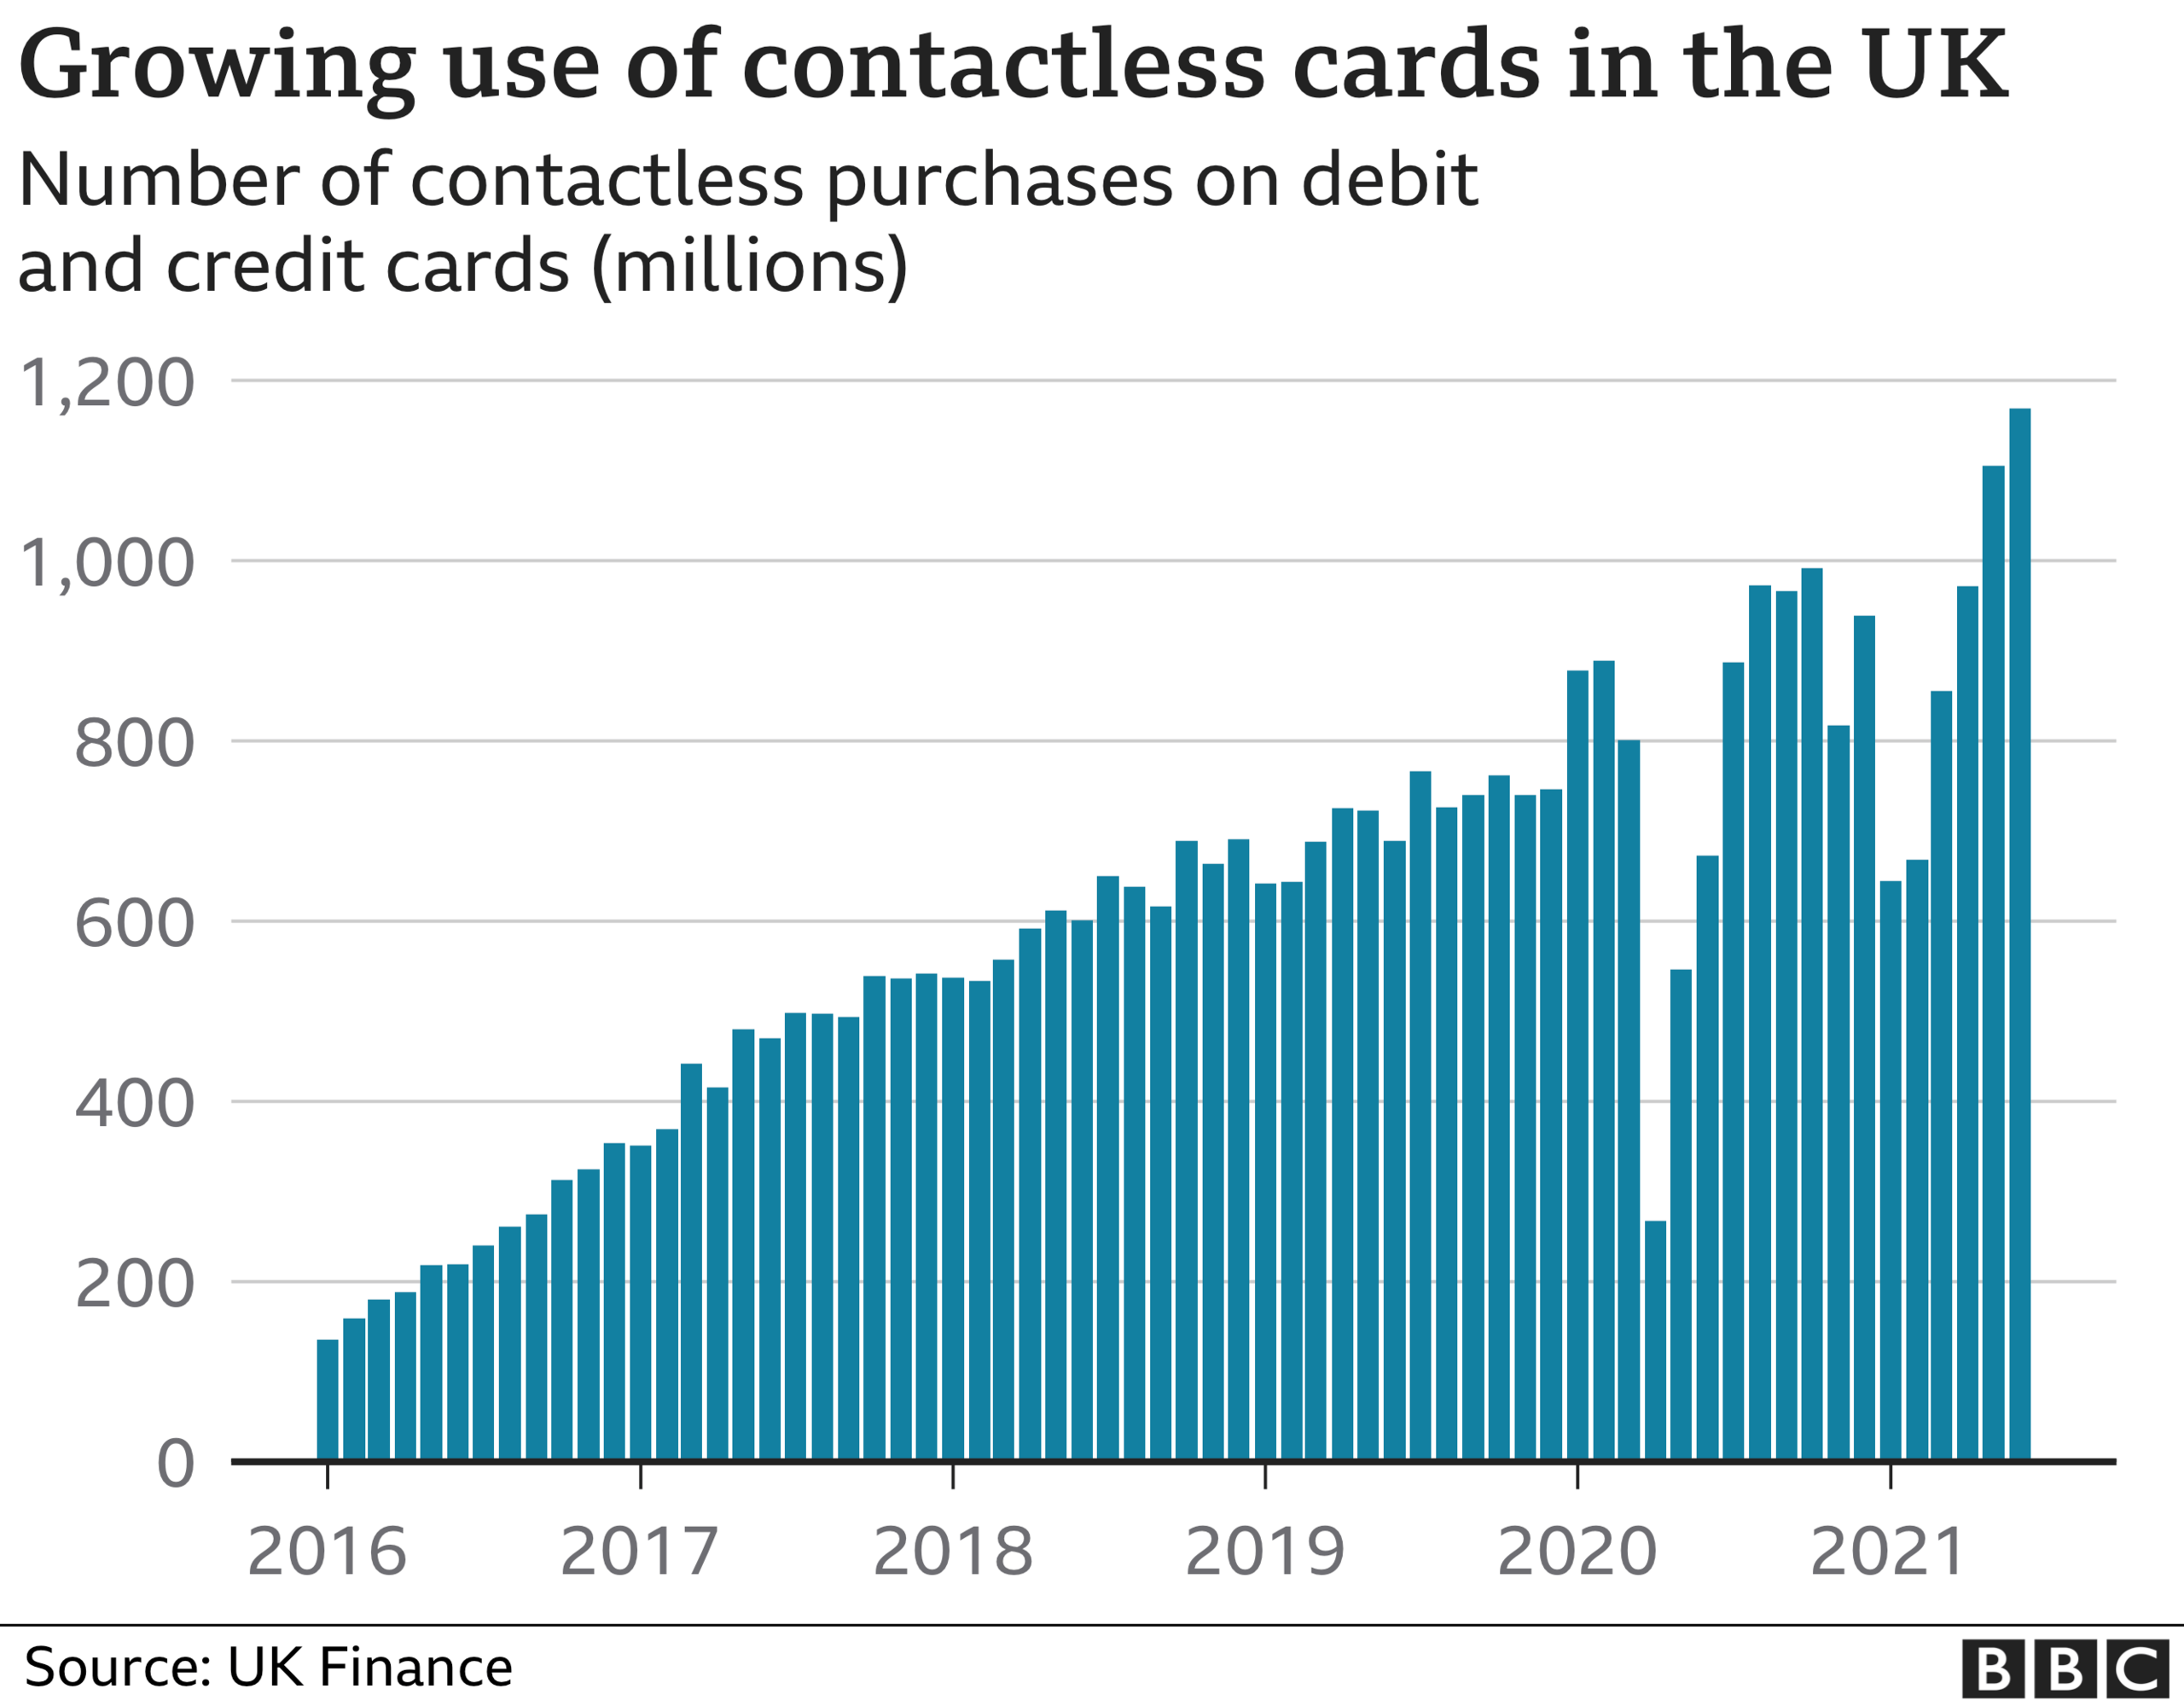
Also, contactless is already the fastest growing payment method in the UK. Making it limitless might push people back to cash, which is slower but safer for big purchases.
And let’s not forget the elephant in the room: loss of control. When you pull out cash for a £300 item, you feel the weight. With a tap, you don’t. That’s how people overspend—and fraudsters thrive.
The irony: We already have a solution—and it’s called the PIN
Here’s my favorite part. The UK could simply keep the current limit or increase it slightly (say, to £200), but instead they’re considering going all the way. Why fix what isn’t broken?
Other countries, like the US, have higher limits but still require a PIN for larger amounts. The UK’s approach—removing limits entirely—feels like driving without brakes because you like the speed.
So, dear reader, what’s your take? Would you feel safe with an unlimited tap? Or does this plan make you want to bury your cash in the garden? Be honest.
For now, I’ll be keeping my card in a RFID-blocking wallet—and watching the news like a hawk. Because convenience is great, but peace of mind is priceless. And that’s the part no tap can buy.