
Cheapest Cars To Insure For First Time Drivers

Let’s be honest: getting your first car is a rite of passage. You’ve finally saved up for that slightly-scratched hatchback that smells faintly of old fries. But then insurance quotes slap you back to reality with a number that feels more like a mortgage payment. That’s the moment you realize you need the cheapest cars to insure—not just the cheapest to buy.
Why insurance costs matter more than the car payment
Think of insurance as that grumpy gatekeeper who decides if you can actually afford to drive. For first-timers, your premium is crazy high because you’re a blank slate—no driving history, just potential mistakes. A cool-looking coupe might look great in your driveway, but it’ll cost you double in monthly premiums.
The trick is to choose a car that insurance companies love. Not because they’re nice, but because it’s cheap to fix and rarely gets stolen. It’s like picking a loyal golden retriever over a hyperactive squirrel—predictable and safe.
Must Read
- Did Kelly Clarkson Just Get Julia Roberts Treatment? The Untold Truth Behind Brooklyn’s $15m Animatronic Bird Drama
- The 5-minute Visit That Broke The Internet: How Kelly Clarkson Sparked A $15 Million Mechanical Bird War
- Petty Revenge Or Viral Genius? Brooklyn Store Slaps $15,000,000 Tag On Molly The Bird After Kelly Clarkson Backlash
The reliable heroes: small hatchbacks and sedans
Picture this: you’re scraping by on a part-time job at a coffee shop, and every dollar counts. The Honda Fit (or Jazz, depending on where you live) is your best friend. It’s tiny, easy to park, and insurance companies barely bat an eye at it. My friend Emma bought one for $4,000, and her premium was about the same as her weekly grocery bill—painless.
Another crowd-pleaser is the Mazda 2. It’s fun to drive (yes, really) and has solid safety ratings. Safety equals lower risk, and lower risk means your wallet doesn’t cry. Imagine telling your parents, “I chose a car that’s actually sensible,” and they don’t laugh. That’s the Mazda 2.
Don’t sleep on the Toyota Yaris
The Yaris is like that reliable friend who always shows up on time. It’s not flashy, but it’s bulletproof. Insurance companies love it because parts are everywhere and cheap. You could literally drop a Yaris off a small cliff (please don’t), and a mechanic could fix it with duct tape and a prayer. Your monthly premium? Often under $100 for basic coverage.
The budget-friendly older models
If new cars scare your wallet, look at a used Ford Fiesta from a few years back. It’s cheerful, zippy, and so common that no one bothers to steal it. Less theft equals a lower premium. Plus, you can name your car “FiFi” and no one judges you.
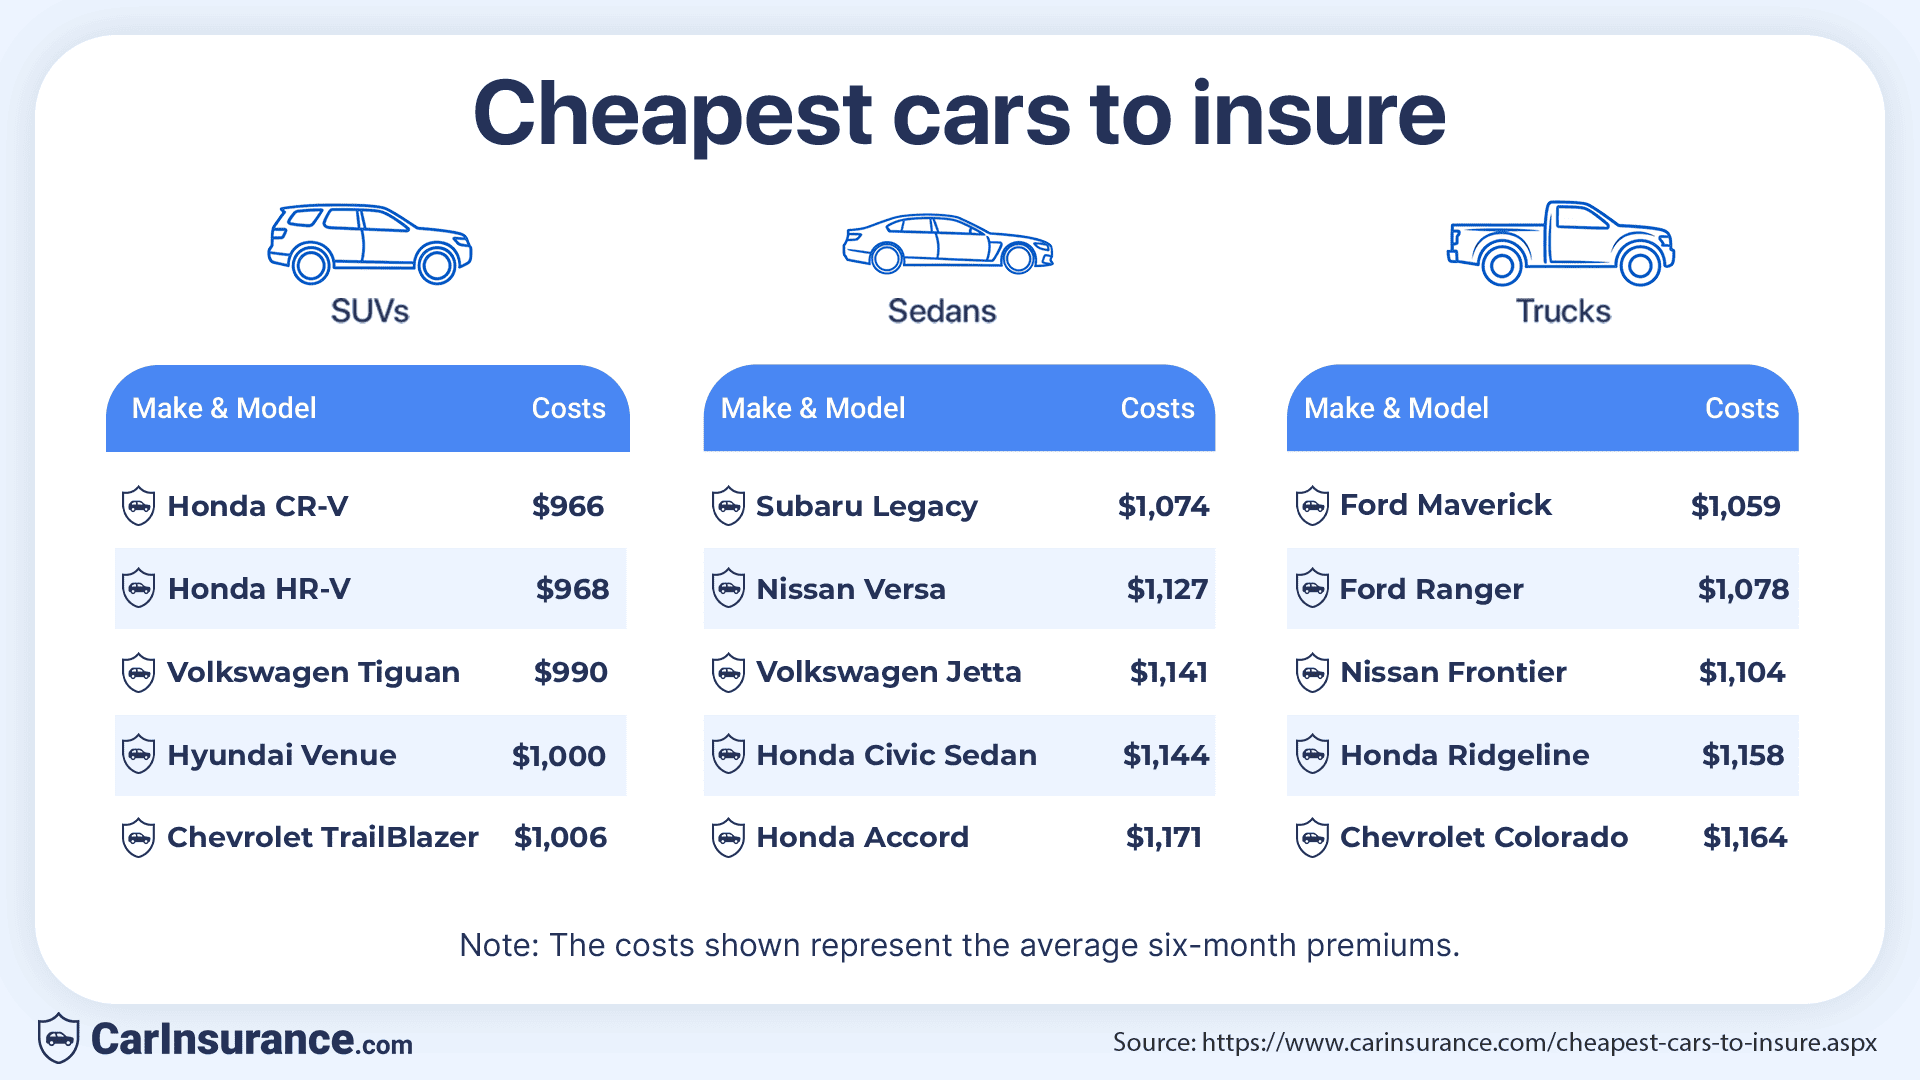
Then there’s the Chevrolet Spark. Yes, it’s small. Yes, you’ll look like an adult in a kid’s pedal car. But it sips gas like a hummingbird, and insurance quotes are comically low. My cousin drove one for three years, and his biggest expense was buying a new air freshener. Reliable and cheap is a beautiful combo.
The “why did no one tell me” list
Let’s get specific. Here’s the top tier of cheapest cars to insure for a first-timer:
- Honda Civic (older models): Safe, reliable, and cheap to repair. Just avoid the sporty trims (insurance sees “sporty” as “fast and dangerous”).
- Subaru Impreza: All-wheel drive sounds fancy, but it’s actually safe and utilitarian. Perfect for rainy climates.
- Kia Rio: It’s like a dependable sandwich—nothing fancy, but it works. Low theft rates make insurers yawn happily.
- Hyundai Accent: Often overlooked, but this car is a secret weapon for low premiums. It’s boring, but boring saves you money.
The one golden rule: skip the “cool” car
You might be tempted by a used Mini Cooper. I get it—they’re adorable. But they’re expensive to fix, and insurers see them as a luxury repair nightmare. I once saw a quote for a young driver at $3,500 a year. That’s more than the car itself!
Instead, embrace the glorious boringness of a practical car. When your friends show off their sporty cars, you can smile and think, “My insurance is cheaper than your gym membership.” That’s a win.

How to make it even cheaper
Even the cheapest car can become pricier if you’re careless. Take a defensive driving course (often free online) and you’ll get a discount. Add yourself as a named driver on a parent’s policy if you still live at home—it’s a weird insurance loophole that works.
Also, consider a black box (telematics) policy. It tracks your driving, but it can slash premiums by 20% if you drive gently. Imagine getting a reward for not speeding past a school. It’s like your car becomes a friendly teacher.
Final thought: your car is your co-pilot
Your first car isn’t a status symbol—it’s a ticket to freedom. A cheap-to-insure car lets you actually enjoy that freedom instead of stressing about monthly payments. You can drive to work, hang out with friends, or take a road trip without wondering if you’ll eat ramen for a month.
So go ahead, pick that used Toyota Yaris or Honda Fit. Park it proudly, smile at the low premium, and remember: your bank account will thank you later. Now get out there and drive—just not too fast.