
How Many Years Contributions For State Pension
Let’s talk about the state pension. Yes, that magical pot of gold at the end of your working rainbow. It sounds boring, but stick with me.
It’s a game of years. Not money, not luck—just pure, stubborn time. How many years do you actually need?
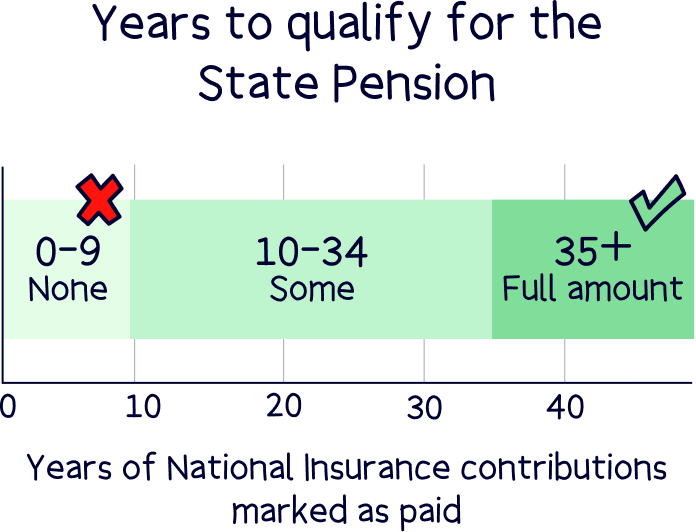
The Magic Number: 35 Years
You need 35 years of National Insurance contributions. That’s the sweet spot for the full, glorious amount.
Must Read
- Did Kelly Clarkson Just Get Julia Roberts Treatment? The Untold Truth Behind Brooklyn’s $15m Animatronic Bird Drama
- The 5-minute Visit That Broke The Internet: How Kelly Clarkson Sparked A $15 Million Mechanical Bird War
- Petty Revenge Or Viral Genius? Brooklyn Store Slaps $15,000,000 Tag On Molly The Bird After Kelly Clarkson Backlash
Think of it as a loyalty card for life. Instead of a free coffee, you get a weekly cheque from the government.
Only 35 years? you ask. Yes! But it’s tricky. They don’t count years you skipped, cried about, or forgot.
What Counts as a “Year”?
It’s not calendar time. It’s tax year time. From April to April. Weird, right?
You need to earn enough in that tax year to get a “qualifying year.” For 2024/25, that’s about £6,725 in earnings. That’s it.
Work one day a week at minimum wage? You might just squeak by. Boom, a year in the bank.
The Quirky Loopholes
Here’s the fun part: you can get free years. Yes, free. Look after a child under 12? That’s a year. Claim Carer’s Allowance? Another year.
Unemployed and on Jobseeker’s Allowance? Yep, that counts too. The state basically hands out credits like candy.
You can even buy missing years. Voluntary contributions—it’s like time travel for your bank account. Go back and fill gaps for 2018 if you want.
The 10-Year Trap
Here’s a nasty surprise: you need at least 10 years to get anything. Zip, zilch, zero if you have less.
Ten years gets you a tiny sliver of pension. Like a single slice of bread instead of a loaf. Don’t fall into the 9-year pit.
That’s right—9 years of work equals nothing. It’s brutal but true. You must cross the double-digit finish line.
The “Why 35?” Mystery
Why 35? Nobody really knows. It used to be 30, then they changed it. Classic government math.

They say it’s to reflect modern careers. You now work longer, so you need more years. Thanks, actuarial tables.
Fun fact: you can have 50 years of contributions. But you only get paid for 35. The extra years? Useless—like a bonus level in a video game with no reward.
The Gap Years
What if you took a gap year to travel? Or quit your job to start a band? Ouch—that year probably doesn’t count.
Unless you were on benefits or self-employed and paid your own stamps. If you just bummed around, it’s a black hole.
But here’s the kicker: you can check your record online. It’s like a report card for your adult life. Shocking, isn’t it?
The “Full” Pension Isn’t Full
Even with 35 years, you don’t get a mansion. In 2024/25, the full new state pension is about £221.20 a week. Nice, but not a yacht.
That’s about £11,500 a year. Enough for groceries, cat food, and a few Netflix subscriptions. Don’t quit your day job yet.
And if you have a private pension, this is just the cherry on top. The state one is the sad, plain cake.
The Funny Part: People Think It’s Automatic
Many assume the state just knows. “I’ve worked all my life! Where’s my money?” Nope—you have to build your record.
There are stories of people with 40 years of work but zero contributions. How? They earned under the threshold each year. Oops.
That’s why checking your record is so important. Don’t be that person who discovers a gap at age 67. Yikes.
The Self-Employed Trap
Self-employed people are especially vulnerable. You pay Class 2 and Class 4 NI. But if you earn little, you might accidentally skip a year.
One bad tax year and boom—a hole in your 35-year armor. Sneaky, right?
Pro tip: file your tax return even if you earn nothing. It keeps your record alive. Tax evasion is bad, but tax ignorance is worse.
The Carer’s Credit Secret
Did you know you can claim Carer’s Credit? If you care for someone 20 hours a week, boom—a free year.
It’s one of the best-kept secrets. The government doesn’t scream it from rooftops. Probably because they don’t want to pay us.
Mothers, fathers, grandkids—if you’re a carer, get that credit. You earned it.
The “I’m Too Young” Myth
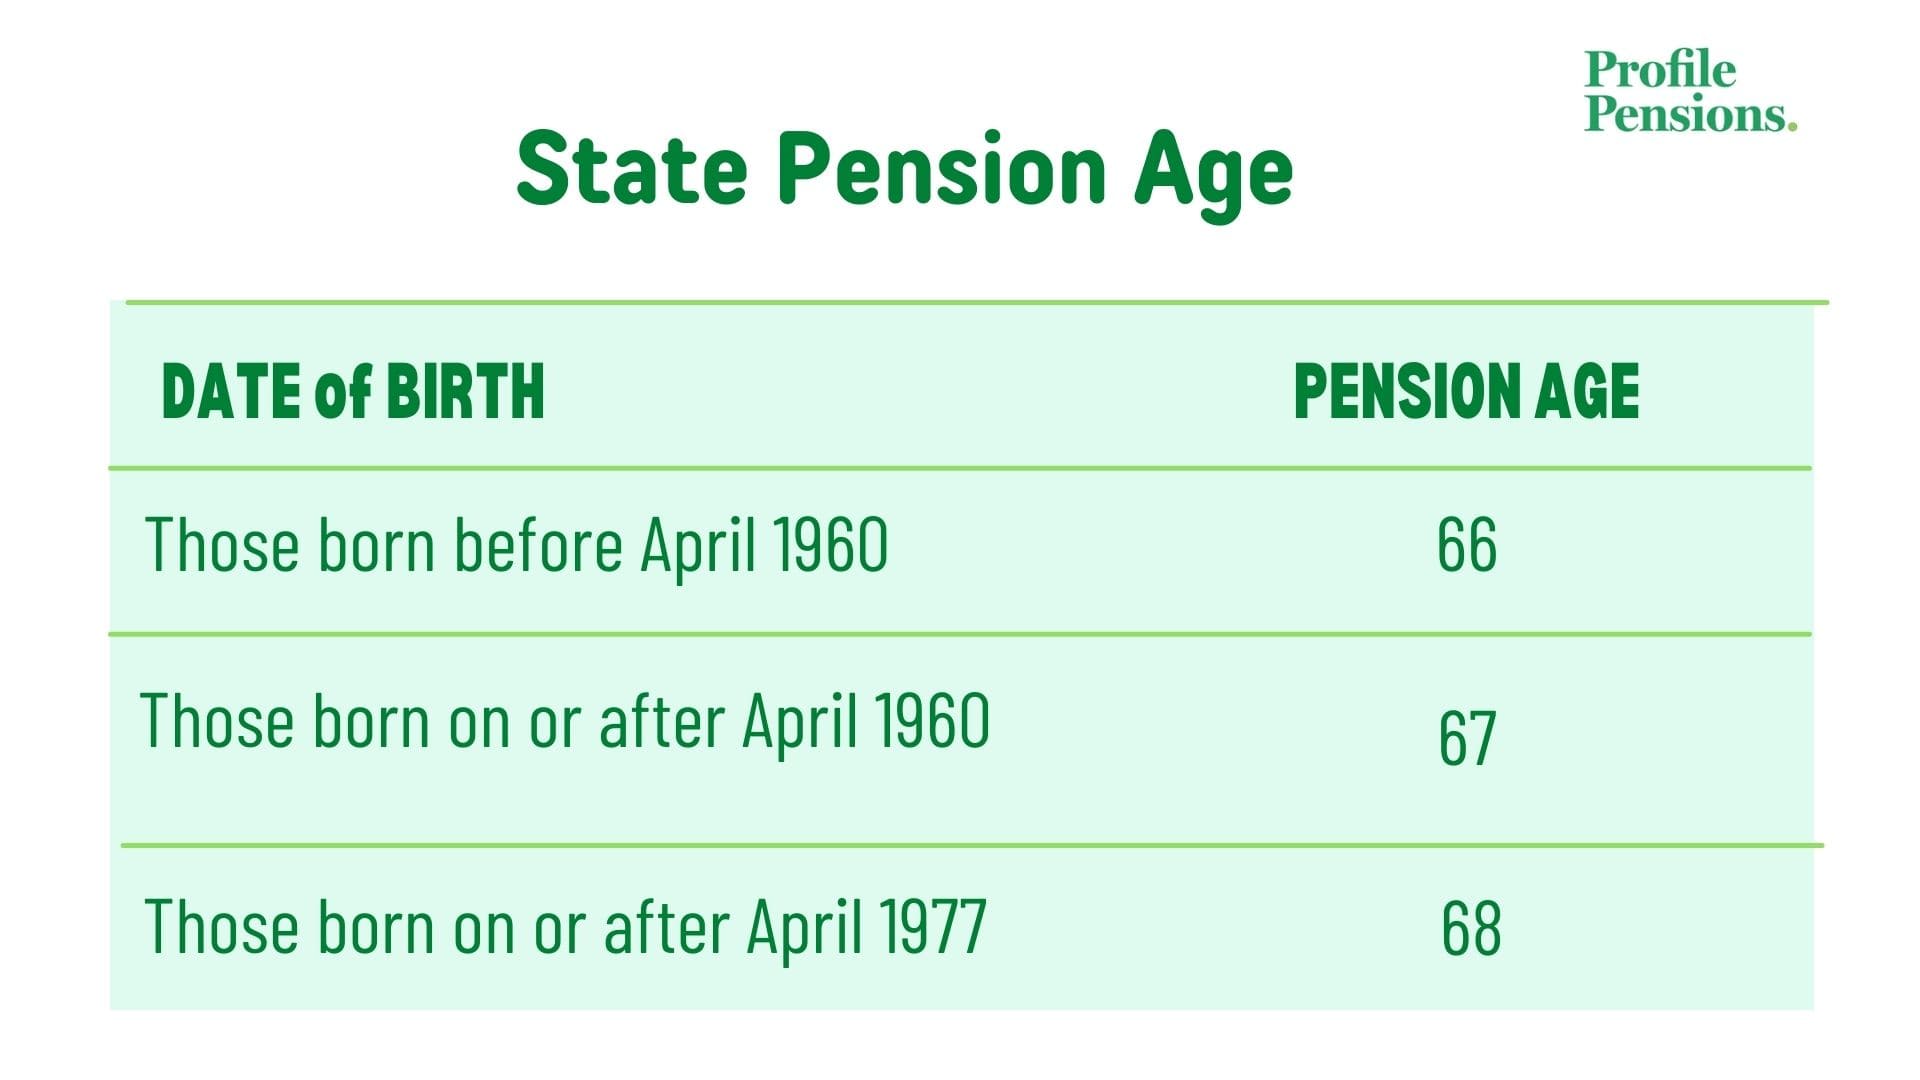
Think you’re too young to care? Wrong. Your state pension age keeps creeping up. It’s already 67 for most people born after 1960.
Some experts say it might hit 70. That means you contribute for decades before seeing a penny. Lovely, huh?
But here’s the upside: you can use those years wisely. Fill gaps early. Buy cheap years while you’re still earning. Future you will high-five present you.
Final Fun Fact: You Can Have a Negative Year
Yes, negative years exist. If you earned too little and didn’t pay NI, the year doesn’t count. It’s a void.
But you can fill it retroactively. Pay for past years up to six years back. After that, it’s gone forever. Gone. Poof.
So check your record now. Not tomorrow, not next week. Right now. Because the state pension is a game of patience, luck, and 35 perfect years.
Go forth, contribute, and don’t let a gap year ruin your retirement dreams. You’ve got this.