
What Happens To Someone's Pension When They Die
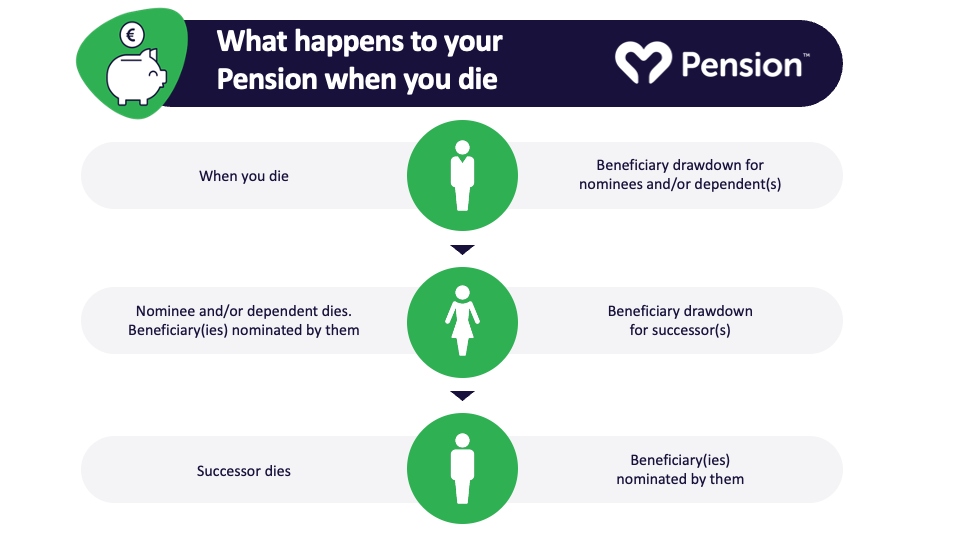
Let’s be honest: thinking about your pension after you’re gone feels a bit like worrying about who gets your leftover pizza after a party you already left. It’s weird, slightly morbid, but absolutely worth understanding. So, what actually happens to that hard-earned pot of money when you shuffle off this mortal coil?
First, the good news: Your pension does not evaporate into the ether like a ghost in a cheap horror movie. It doesn’t get scooped up by some mysterious government vault. Instead, it becomes a little treasure hunt for the people you leave behind.
The answer depends entirely on the type of pension you have. Think of it like this: a pension is either a big, shared pizza (a defined benefit plan) or your own personal, carefully-wrapped leftover slice (a defined contribution plan). The rules for what happens to each are surprisingly different.
Must Read
- Did Kelly Clarkson Just Get Julia Roberts Treatment? The Untold Truth Behind Brooklyn’s $15m Animatronic Bird Drama
- The 5-minute Visit That Broke The Internet: How Kelly Clarkson Sparked A $15 Million Mechanical Bird War
- Petty Revenge Or Viral Genius? Brooklyn Store Slaps $15,000,000 Tag On Molly The Bird After Kelly Clarkson Backlash
The “Shared Pizza” Pension (Defined Benefit)
This is the old-school pension from your grandpa’s factory job—a monthly check for life. If you die before retiring, this one plays hard to get. Usually, your spouse gets a smaller version of that monthly check, like a “survivor’s benefit” that’s about half or two-thirds of what you would have received.
But here’s the kicker: if you die after you’ve already retired, the rules can change. If you took the “single life” payout (more money for you each month), the checks stop cold when you die. Sorry, kids. It’s like ordering the large pizza, eating all the slices yourself, and leaving the box empty.
However, if you chose the “joint life” option with your spouse (a slightly smaller check each month), the payments keep going to them for the rest of their life. It’s the financial equivalent of saying, “I had a slice, but I saved you a whole half.” It’s a romantic gesture, buried in actuarial tables.
What About the “Personal Slice” Pension? (Defined Contribution)
This is the 401(k) or IRA—your own little retirement piggy bank. This is where things get much simpler and, frankly, more generous. That entire pot of money? It belongs to your estate or to a named beneficiary.

If you named your spouse, they can usually roll it into their own retirement account without a tax hit. They can treat it like it’s their own pizza now. If you named your daughter, your friend, or even your cat (if you’re weird enough), they get the entire leftover slice.
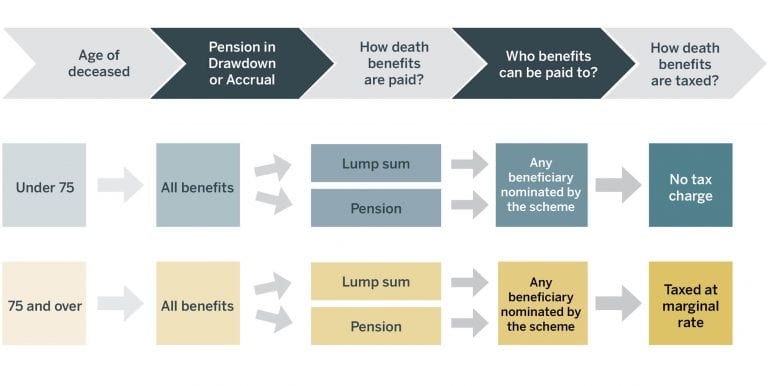
The tricky part is the inheritance tax. Depending on your country, your beneficiaries might have to pay a slice of that pizza back to the taxman. It’s like ordering delivery and realizing you have to tip the driver before you can eat.
The Ultimate “What If?”: No Beneficiary Named
Here’s where the story gets mildly tragic. If you die and you haven’t named a beneficiary—maybe you forgot, or you’re just too relaxed—your pension goes to your estate. This means it goes through probate.
Probate is like a slow, bureaucratic game of “Who Wants This Money?” Courts get involved. Lawyers send letters. It takes months, sometimes years, and fees eat up a chunk of that cash. It’s like leaving your pizza in the break room fridge with no name on it—eventually, someone picks it apart, and no one gets a full meal.
The Funny Anecdote That Will Stick With You
I once knew a guy named Bob who was obsessed with pensions. He had spreadsheets. He had actuarial predictions. He talked about “portability” at parties. When Bob passed away suddenly at 72, his wife, Linda, found his pension paperwork in a folder labeled “Top Secret Pizza Plans.”
Linda thought she’d be rich. Turns out, Bob had chosen the “single life” payout because it gave him an extra $200 a month. So the day Bob died, the pension checks stopped. Linda got nothing from that plan. She did, however, inherit his massive collection of novelty pens. Moral of the story? Bob was a bad planner, and his pizzeria closed without notice.
So, What Should You Do?
First, name a beneficiary. Right now. Even if it’s just a placeholder. It’s easier than choosing a Netflix movie. Second, if you have a spouse, talk about the joint-life option. It might mean a slightly smaller sandwich today, but it prevents your partner from being hungry tomorrow.
And finally, remember that your pension isn’t just for you—it’s a little love letter to the people stuck dealing with your estate. Don’t let it become a nasty surprise. Because nothing says “I love you” like leaving a well-planned, tax-efficient pile of cash behind.
So go ahead, smile at the thought. Your pension is a cozy blanket you’ll leave behind. Just make sure your loved ones know where to find it, and how to use it—without having to decipher a spreadsheet from the 1980s.