
Why Would Universal Credit Ask For Bank Statements
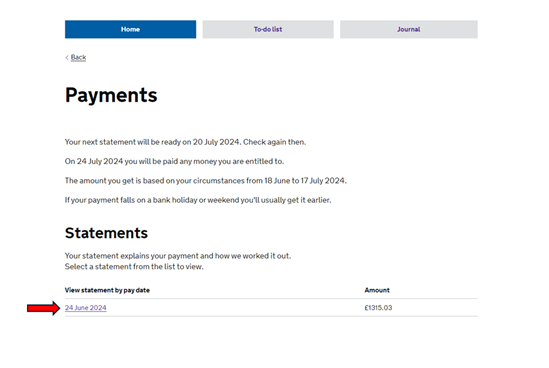
So, picture this. It’s a dreary Tuesday morning, and you’re halfway through your second coffee when a notification pings on your phone. It’s from Universal Credit. They want something. Spoiler alert: it’s not a compliment about your recent job search. They want bank statements.
Your brain immediately goes into overdrive. Did I mess up my reporting? Are they about to freeze my payment? Did that weird £20 I lent my mate yesterday suddenly look suspicious? You’re not alone. Everyone feels that little jolt of panic. But let’s take a step back and look at why they’re actually asking—because, believe it or not, it’s not always a trap.
The Real Reason They’re Digging Into Your Account
First, the boring but true answer: Universal Credit is a means-tested benefit. This means the amount you get depends entirely on what’s coming in and what’s sitting in your accounts. They need to verify that what you told them matches reality.
Must Read
- Did Kelly Clarkson Just Get Julia Roberts Treatment? The Untold Truth Behind Brooklyn’s $15m Animatronic Bird Drama
- The 5-minute Visit That Broke The Internet: How Kelly Clarkson Sparked A $15 Million Mechanical Bird War
- Petty Revenge Or Viral Genius? Brooklyn Store Slaps $15,000,000 Tag On Molly The Bird After Kelly Clarkson Backlash
Think of it like a reality check. You tell them you have zero savings and only earned £200 last month. But if your bank statement shows a shiny £1,000 deposit from a freelance gig you forgot to mention—well, red flag. They’re just checking for consistency, not trying to catch you out for fun.
Another big reason? They’re looking for capital. In UC land, if you have over £6,000 in savings, your payment starts to shrink. Over £16,000? You’re usually not eligible at all. So when they ask for statements, they’re basically asking, “Hey, are you hiding a secret savings account under your mattress?”
The “Weird Deposit” Mystery
Ever had a friend transfer you £50 for dinner and suddenly your payment is on hold? It happens. Universal Credit wants to distinguish between a gift, a loan, and income. A loan from mum isn’t “income” (they don’t tax your birthday cash), but a regular payment from a side hustle? That’s different.
If you see a request for statements, it’s often because a single transaction looks odd. Maybe you sold an old sofa on Facebook Marketplace for £100. To you, it’s a clear-out. To a computer algorithm, it looks like “unreported earnings.” So they ask for proof to say, “Explain this, please.” It’s annoying, but it’s their job.
And here’s the irony: sometimes you trigger the review yourself. If you call them to report a change—like starting a new job or moving house—they might flag your account for a “random” statement check. Coincidence? Probably not. It’s like you’ve just poked a sleeping bear with a stick.
What About “Proving You’re Actually Broke”?
Okay, let’s be real for a second. Sometimes you don’t have any suspicious deposits. You’re genuinely scraping by. And yet, they still ask. Why? Because the system is built on trust, but also on paperwork. A statement confirms you’re not secretly wealthy or working cash-in-hand.
Believe it or not, some people do try to cheat the system—like someone working under the table while claiming full benefits. So the rest of us get dragged into the same net. It’s frustrating, but it’s the price of a safety net that relies on self-reporting.
Here’s the kicker: if your statement shows you’ve been overdrawn for three months and living off food banks, they usually see that and think, “Cool, they’re fine.” But if it shows you spent £300 on a concert ticket last week? That might raise an eyebrow—not because you can’t have fun, but because they question how you afforded it on a low income.
The “Delay” Trap You Should Know About
One thing nobody tells you is that asking for statements is often a bureaucratic delay tactic. Your work coach might have a deadline to review your claim. By requesting statements, they buy themselves time. Meanwhile, your payment gets stalled.
This is the part that makes me ironic-chuckle. You’re rushing to upload digital scans, while the person on the other side might be sipping tea, thinking, “I’ll get to this in a week.” You are the priority to you, but not always to them. So upload those statements fast, but expect a wait.
Also, never think they don’t check joint accounts. If you live with a partner, they want their statement too. Their income counts as yours in UC world. That “roommate” you live with? If you’re a couple, UC will treat you as one unit. So yes, your partner’s £500 bonus from work can affect your payment. Sorry, not sorry.
How to Not Panic (and What to Do Next)
So, you get the request. What now? First, take a breath. It’s usually a random review or a specific query. If you’ve reported everything honestly, you’re fine. Gather statements for the last four months (that’s the standard request).
Don’t crop or redact anything. They need to see every transaction—yes, even the Tesco meal deal and that suspicious donation to a Twitch streamer. If you hide something, it looks like you’re hiding something bigger. Trust me, they’ve seen it all.
Finally, remember: you have rights. If you think the request is unreasonable, you can ask for a mandatory reconsideration. But honestly? Unless you’re a secret millionaire, just send the damn statements. It’s easier than fighting a faceless system.
So, next time you see that dreaded request, don’t sweat it. Think of it as a clumsy audit from a clumsy system. And if all else fails, just imagine your work coach trying to decipher why you spent £4.50 on a fancy oat latte last Wednesday. They can’t judge you—they’re probably drinking instant coffee.