
What Happens To A Private Pension When Someone Dies
Let’s face it: planning for the end of life sounds about as fun as a root canal while folding laundry. But when a loved one passes, their private pension doesn’t just disappear like that weird Tupperware in the back of your fridge. Oh no, it has a whole little playbook of rules, and understanding it can save you from a paperwork headache the size of a small planet.
Think of a private pension like a subscription to a streaming service that you pay for but your grandma actually watches. When the subscriber dies, the question is: does the service keep playing, or does it turn into a brick? It all depends on the type of pension they had, because pensions, like cats, have very distinct personalities.
The Two Big Personality Types: Defined Benefit vs. Defined Contribution
You’ve got a defined benefit pension—the old-school, "promise you a monthly paycheck forever" kind. Your dad might have worked forty years at the phone company for that. When the person dies, the pension usually stops paying the full amount, but a spouse or a dependent kid might get a reduced survivor benefit, like a watered-down coffee instead of the double espresso.
Must Read
- Did Kelly Clarkson Just Get Julia Roberts Treatment? The Untold Truth Behind Brooklyn’s $15m Animatronic Bird Drama
- The 5-minute Visit That Broke The Internet: How Kelly Clarkson Sparked A $15 Million Mechanical Bird War
- Petty Revenge Or Viral Genius? Brooklyn Store Slaps $15,000,000 Tag On Molly The Bird After Kelly Clarkson Backlash
Then there’s the defined contribution pension—think 401(k)s and personal pots of money. This is like a savings account that got a gym membership and started calling itself a pension. When the owner dies, that entire pot of cash belongs to their estate or a named beneficiary, kind of like finding a forgotten $20 in a winter coat.
Who Gets the Keys to the Money?
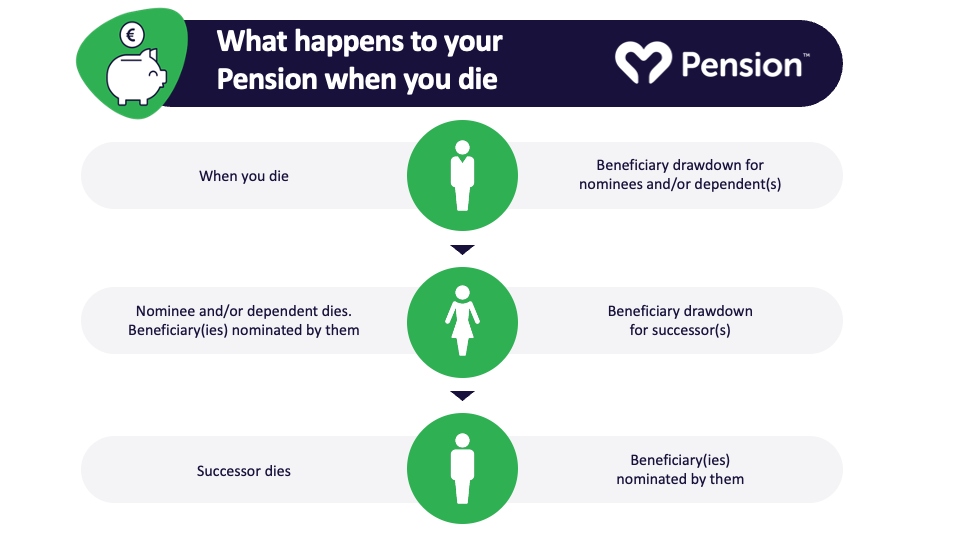
If the deceased filled out a beneficiary form—and please, for the love of spreadsheets, tell your relatives to do this—the money goes straight to that person. It’s like a VIP pass that bypasses the slow line of probate court. My Aunt Carol once forgot to update her form after her divorce, and her ex-husband Bob got her pension. Bob used it to buy a jet ski. The family still brings it up at Thanksgiving.
But if there’s no beneficiary named? Well, welcome to the bureaucratic fun zone. The pension pot goes into the estate, which means the courts, lawyers, and a whole lot of forms get involved. It’s like losing your boarding pass and having to argue with the airline for two hours—while wearing pajamas in public.

What If They’re Already Receiving Payments?
Here’s where it gets sticky. If your Uncle Dave was already collecting his monthly pension check, that check stops the month he dies. Yes, you cannot keep cashing it. The pension company will send a final payment, and then it’s done—like a TV show that ends on a cliffhanger. If Dave chose a “joint and survivor” option (meaning it keeps paying his spouse), then his wife, Aunt Linda, gets 50% to 100% of that check for the rest of her life. Smart Dave.
But if Dave chose a “single life” option to get bigger checks while he was alive? When he goes, the pension goes kaput. It’s like ordering the giant bucket of popcorn but forgetting you have to share the bathroom later. Spouses should always, and I mean always, ask about this before retirement. Nobody wants to learn about survivor benefits while holding a casserole and a calculator.
The Tax Man Cometh (Of Course)
You thought you could just take the money and run? The IRS wants a dance. If the pension is a lump sum paid to a beneficiary, it’s taxed as ordinary income for that year. Imagine getting a bonus at work, except the bonus is your dead uncle’s retirement fund. It can push you into a higher tax bracket faster than you can say “I hate April 15th.”
But here’s a little trick: if the beneficiary is a spouse, they can roll the pension over into their own IRA without any tax hassle. It’s like transferring your leftover pizza to a new box—no waste, no mess. Non-spouse beneficiaries, like your cousin Kevin, have to take the money out within ten years, per the SECURE Act. Kevin will probably use it for a down payment on a van to live in.
The Quiet, Awkward Part: What If You’re Not the Spouse?
If you’re a sibling, a friend, or a “trusted neighbor” listed as a beneficiary, you’re called an non-spouse beneficiary. You get the money, but you have to follow the “10-year rule.” That means you can take it all at once (and cry at the tax bill) or stretch it out over a decade. It’s like being told you can eat the whole cake, but you must do it in ten slices. Many people take it all at once, buy a new car, and then regret it when they realize the car insurance is more than their rent.
I knew a guy named Jerry who inherited a modest pension from his godmother. He took it as a lump sum, bought a vintage sailboat, and named it “The Tax Deduction.” The sailboat sank three weeks later. The lesson? Don’t be Jerry. Talk to a financial advisor before you touch a dime.
The Bottom Line (Wrapped in a Fist Bump)
Here’s the easiest way to remember all this: if the pension is a promise to pay for life, it usually dies with the person—unless they made a pact to share it with a spouse. If the pension is a personal pot of money, it goes to whoever’s name is on the form. Fill out that form. Update it when you get married, divorced, or just feel like your brother doesn’t deserve a jet ski.
Death is messy, confusing, and full of paperwork that nobody wants to read. But understanding your pension options is like knowing the location of the emergency exit—it’s boring until you need it, and then it’s the best thing in the world. So go on, ask your parents or your partner: “Hey, who’s your pension beneficiary?” It might be the most awkward conversation you have this year, but it’s a lot better than accidentally funding a jet ski for Bob.