
How Many Years To Contribute For Full State Pension
Let’s be honest: when you’re twenty-something, the state pension feels about as real as a unicorn in a tuxedo. You’re just trying to afford avocado toast and a Netflix subscription, not worrying about some mythical pot of gold at the end of a forty-year rainbow. But one day, usually after your third cup of coffee and a particularly boring spreadsheet, it hits you: How many years do I actually need to pay into this thing to get the full whack? Well, grab your calculator and a strong drink, because the answer is weirder than you think.
The Magic Number: It’s Not What You Expect
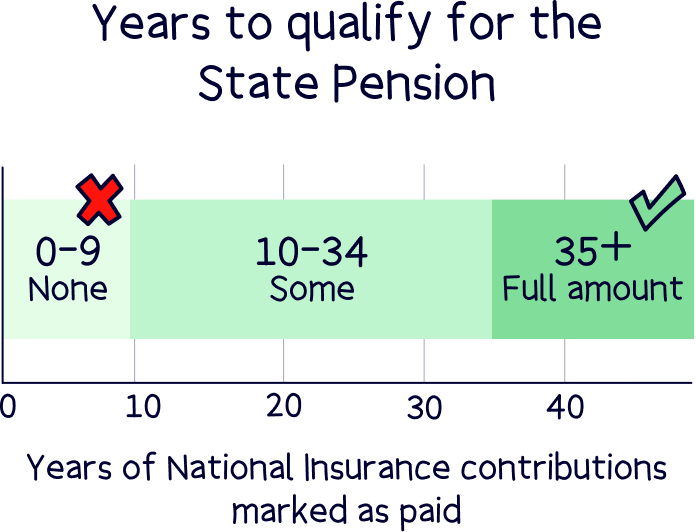
For the full State Pension (that’s the new, post-2016 version), you need a solid 35 years of National Insurance contributions. Yes, thirty-five. That’s longer than most celebrity marriages and roughly the same amount of time it takes for your favorite pair of jeans to finally fall apart. If you haven’t got those 35 years, your pension pot shrinks faster than a wool sweater in a hot wash.
But here’s the kicker: you don’t have to work for 35 straight years. You could be a pirate for a decade, a professional cat-sitter for five, and a YouTube philosopher for the rest, as long as you pay those National Insurance credits. The system is surprisingly forgiving, which is probably the first time anyone has used the words “National Insurance” and “forgiving” in the same sentence.
Must Read
- Did Kelly Clarkson Just Get Julia Roberts Treatment? The Untold Truth Behind Brooklyn’s $15m Animatronic Bird Drama
- The 5-minute Visit That Broke The Internet: How Kelly Clarkson Sparked A $15 Million Mechanical Bird War
- Petty Revenge Or Viral Genius? Brooklyn Store Slaps $15,000,000 Tag On Molly The Bird After Kelly Clarkson Backlash
What Counts as a “Year”? (Spoiler: Not Much)
A qualifying year doesn’t mean you worked 365 days. Oh no, that would be too sensible. You just need to earn above a certain threshold—for 2024/2025, that’s about £6,396 in a job. That’s roughly the cost of a second-hand car that makes worrying noises. So if you work one day a week as a part-time potter and somehow earn enough, congratulations: you just bagged a whole year toward your pension.
The real comedy begins when you realize that gaps in your record happen when you’re being a responsible human. Took a year off to raise a child? That’s a National Insurance credit (thank you, Child Benefit). Were you unemployed and claiming certain benefits? Those years might count too. Basically, the system loves it when you’re either working or officially miserable.
The “Ten-Year Trap” Nobody Warns You About
Here’s a shocking, sofa-falling-over fact: you don’t need 35 years just to get any state pension. You only need 10 qualifying years to unlock the base amount. That’s the bare minimum, the “I-showed-up-once-a-decade” special. If you have 10 years, you get a portion. But if you have 34 years? You’re one year short of the full amount, and you’ll get about 97% of it. Talk about a tease—it’s like running a marathon and stopping at mile 25.9 because your shoelace came undone.

Believe it or not, there are over 200,000 people in the UK who have exactly 30 to 34 years of contributions. They’re so close to the full pension they can taste it, but they’re stuck in a bureaucratic no-man’s land. It’s the pension equivalent of having all the ingredients for a cake except the sugar. You can still bake it, but it’s going to be sad and sour.
The Sneaky Way to Fill Gaps (Voluntary Contributions)
If you discovered you’re missing a year, don’t panic—you can buy it back. The government lets you pay voluntary Class 3 National Insurance to fill holes in your record, and it usually costs around £824 for a full year. That’s a lot of money, sure, but consider this: each missing year reduces your weekly pension by about £5.30. Over a 20-year retirement, that missing year costs you over £5,500 in lost payments. So spending £800 to save £5,500 is like finding a £20 bill on the street and buying a lottery ticket that actually wins.
One guy I know spent two years living in a van in New Zealand, surfing and eating ramen. He came back, checked his record, and found a three-year gap. He bought them back for a total of £2,472. Now he tells everyone, “Best money I ever spent—I basically bought myself a month of retirement per year.”
The Big Gotcha: The Pension Age Keeps Moving
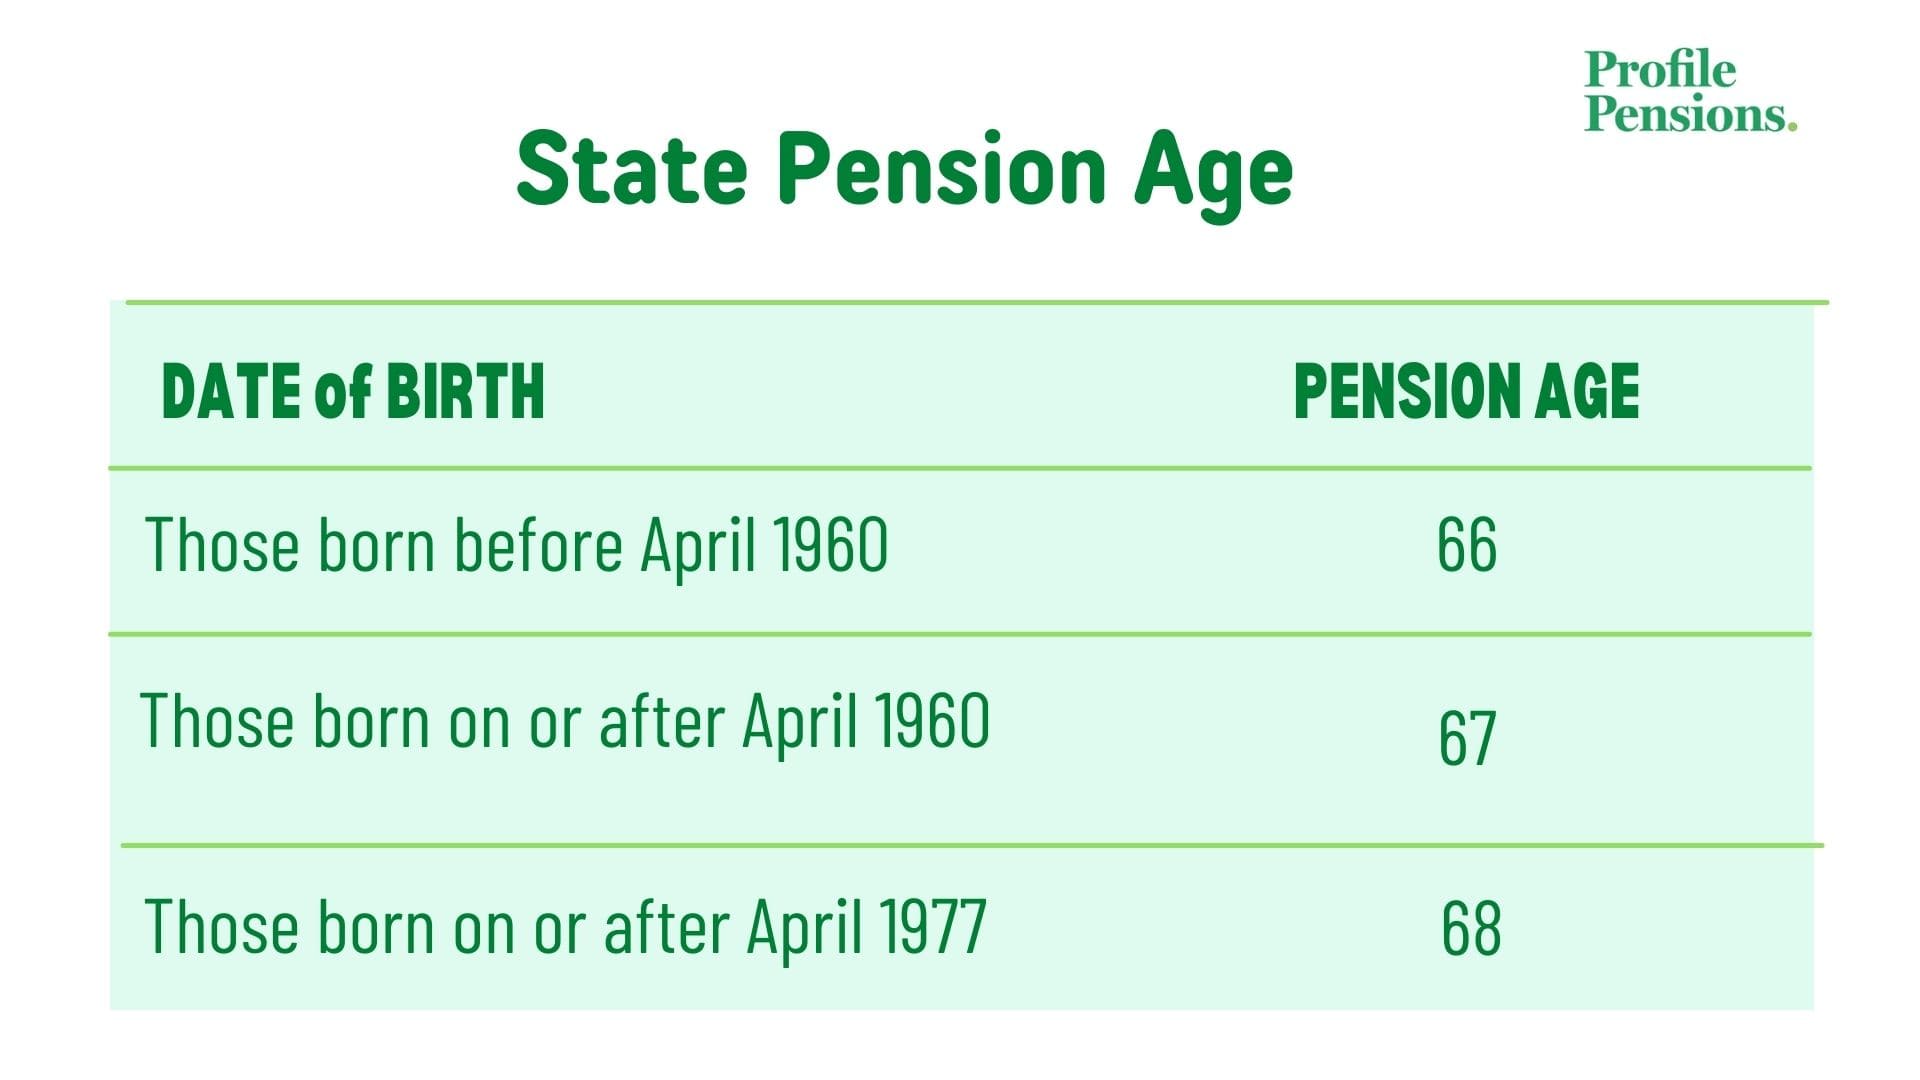
Here’s the punchline that’s more bitter than a double espresso: even if you hit 35 years, you can’t claim the pension until you reach State Pension age, which is currently 66 and rising steadily toward 67 and 68. By the time you’re ready to retire, the age might be 72 and you’ll be expected to collect it via hologram. The government keeps moving the goalposts because—surprise—people are living longer, and the pension pot is, as they say, “under strain.” Under strain? It’s like a balloon at a porcupine convention.
But here’s the genuinely funny part: most people don’t know their own record. A 2023 survey found that 60% of workers couldn’t guess how many qualifying years they had. That’s like driving a car and not knowing how much gas is in the tank. You’re just hoping the engine doesn’t cough.
What You Should Actually Do (The Caffeinated Conclusion)
So, how many years? 35 for the full amount, 10 for the bare bones. Check your National Insurance record online today (it takes three minutes, less time than you spend agonizing over a microwave meal). If you see gaps, consider buying them—but only if you’ll live long enough to enjoy it. The state pension is a strange, grumpy, lovable beast. Feed it your 35 years, and it will hand you a decent slice of pie. Skimp on it, and you’ll be eating toast for dinner at 80. And nobody wants that, especially not with avocado.