
What Happens To Pension If You Die Before Retirement

So, you’ve been diligently stuffing money into a pension pot. You picture yourself sipping cocktails on a beach, finally retired. But then a dark, hilarious thought pops in: What happens if I kick the bucket before I ever get to sip that piña colada? Don’t worry—it’s not as gloomy as it sounds. It’s actually a fantastic brain teaser with surprisingly fun twists.
Your pension isn’t a black hole
First, the good news: your pension is your money (mostly). It doesn’t vanish into a corporate void the second you stop breathing. Think of it as a locked treasure chest. If you die before retirement, your named beneficiary gets the key.
But here’s the quirky bit: the rules depend entirely on what type of pension you have. Two main flavors exist: defined benefit (fancy employer plans) and defined contribution (your own savings pot). They behave like very different animals when you die.
Must Read
- Did Kelly Clarkson Just Get Julia Roberts Treatment? The Untold Truth Behind Brooklyn’s $15m Animatronic Bird Drama
- The 5-minute Visit That Broke The Internet: How Kelly Clarkson Sparked A $15 Million Mechanical Bird War
- Petty Revenge Or Viral Genius? Brooklyn Store Slaps $15,000,000 Tag On Molly The Bird After Kelly Clarkson Backlash
The defined contribution plan: a cash lottery
This is the most common for millennials and Gen Z. It’s basically a giant piggy bank you and your employer fill. Die early? Your beneficiary inherits the full pot—often tax-free if you die before age 75. Yes, you read that correctly: tax-free.
Imagine your nephew suddenly gets £200,000 because you tragically choked on a grape. It’s morbid, but also a little bit funny. They can take it as a lump sum or a steady income. Bonus quirk: If you’re under 75, the government effectively throws a party for your heirs—no income tax, no inheritance tax. It’s like you planned a surprise inheritance party from the afterlife.
The defined benefit plan: a confusing handshake
Old-school employer pensions (final salary schemes) are more dramatic. They pay you a guaranteed income for life. Die before retirement? The rules read like a secret code. Usually, your spouse gets a reduced pension, often 50% of what you would have received.
But here’s the wild part: if you die before you start taking the pension, that spouse might get a lump sum equal to your own contributions plus interest. Or a guaranteed payment period of up to 10 years. It’s a bureaucratic riddle. One pension expert told me: “It’s like trying to predict the weather in a hurricane.” Fun, right?

The lucky loophole: the death-in-service windfall
This is the juiciest part. Many employers have a secret feature called death in service benefit. It’s not technically your pension, but it’s attached. If you die before retiring, your employer pays a lump sum—usually four times your salary—to your family.
So, if you earn £50,000 and die unexpectedly, your beneficiaries get a cool £200,000 completely separate from your pension pot. It’s like winning the lottery, but the ticket is your untimely demise. Dark humor aside, it’s a huge reason to check your benefits package now. You might discover you’re worth more dead than alive—which is a weird but oddly motivating fact.
What about the state pension?
Ah, the state pension—the government’s slow-motion gift. Die before retirement? You get nothing for yourself. But your spouse or civil partner can inherit a slice, called the inherited state pension. It’s tiny—usually around 50% of your projected amount.
However, if you never claimed it? That’s it. The money evaporates. The UK government keeps it. It’s the ultimate plot twist: you spent 40 years paying National Insurance, and your reward is a ghostly “sorry, you’re dead.” But hey, it’s a great conversation starter at parties.
Why you should care (and laugh about it)
This topic is fun because it flips the script on boring retirement planning. You’re not just saving for yourself; you’re building a weird, posthumous treasure map. Pro tip: Name a beneficiary on your pension forms. Seriously. Without one, the money goes to your estate, which gets delayed in probate court for months.
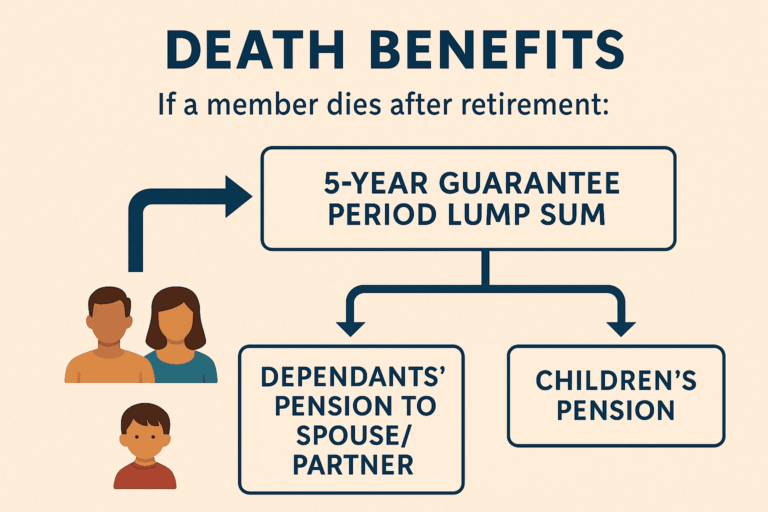
Also, consider a pension death benefit nomination. This lets you choose who gets the cash—even a charity or your weird cousin who collects vintage toasters. Yes, you can leave your pension to a toaster collector. That is a real possibility.
The most surprising fact of all
Here’s a punchline that will blow your mind: if you die after you’ve started drawing your pension but before you’ve used up your pot, the remaining money can still be inherited. It’s not “use it or lose it” anymore. Since 2015, UK pension rules allow the leftover pot to pass to your beneficiaries entirely tax-free if you die before 75.
So the guy who retires at 65, takes out just enough for a fish-and-chips lunch every week, then dies at 74? His kids get a bonus. It’s the ultimate “I told you so” from the afterlife. You can game the system by living cheaply in early retirement.
Final thought: it’s a party, not a funeral
Planning for your pension’s death is oddly joyful. It forces you to imagine your loved ones celebrating your life with a big, tax-free check. It’s the only time in finance where “you died” sounds like good news. So go ahead: update that beneficiary form. Pick a funny beneficiary. Tell your partner they’re getting a golden parachute if you eat too many oysters.
Death is inevitable, but your pension’s fate doesn’t have to be a boring mystery. It’s a quirky, human comedy of errors and loopholes. And if you’re reading this while alive? Congratulations—you still have time to make your death a financial triumph. Now go annoy your friends with this knowledge.