
Royal London Stocks And Shares Isa Review
So, you’re thinking about investing, huh? Maybe you’ve seen the ads for Royal London’s Stocks and Shares ISA and thought, “Hmm, that sounds fancy, but what’s the catch?” Well, grab a cuppa, and let’s chat about it like we’re dissecting the latest office gossip. No jargon, no stuffy suits—just the honest, funny truth.
First Things First: What Even Is a Stocks and Shares ISA?
Think of it as a tax-free treasure chest for your money. Normally, when you invest, the taxman wants a slice of your profits—like that friend who always asks for a bite of your chips. But with an ISA, you keep all the chips. Royal London just gives you a pretty box to store them in, while you pick what goes inside: shares, bonds, or their ready-made funds.
But here’s the kicker: you’re not allowed to touch it until you’re 18. Wait, no—that’s a child’s ISA. For adults, you can withdraw anytime, but please don’t. It’s like a pizza: don’t pick the pepperoni off before it’s baked. Patience, my friend.
Must Read
- Did Kelly Clarkson Just Get Julia Roberts Treatment? The Untold Truth Behind Brooklyn’s $15m Animatronic Bird Drama
- The 5-minute Visit That Broke The Internet: How Kelly Clarkson Sparked A $15 Million Mechanical Bird War
- Petty Revenge Or Viral Genius? Brooklyn Store Slaps $15,000,000 Tag On Molly The Bird After Kelly Clarkson Backlash
Royal London: Who Are They?
Royal London has been around since 1861—older than your great-grandma’s teapot and probably just as sturdy. They’re a mutual company, meaning they’re owned by their members, not by greedy shareholders. So when they say “we put you first,” they’re not just blowing smoke up your ISA. It’s refreshing, like finding a fiver in an old coat.
They specialize in ethical investing, too. That means your money won’t secretly fund a factory that pollutes rivers or makes cute puppies sad. Instead, it might go into wind farms or sustainable companies. Eco-friendly AND profitable? It’s like having your kale smoothie and eating it too.
The Nitty-Gritty: Fees and Minimums
Let’s talk money, honey. Royal London’s fees are pretty cheeky—in a good way. Their platform fee is just 0.40% per year, which is lower than most big banks. No sneaky exit fees, no “we lost your paperwork” charges. That’s like walking into a pub and buying a round for everyone without a hidden tax. Rare.
You can start with as little as £25 a month. Twenty-five quid! That’s less than a takeaway curry for two, and this one actually grows over time (unlike your waistline, no offense). If you’re a newbie, this low barrier to entry is a game-changer. No need to be a millionaire; just a person with a spare twenty-five and a dream.
What About Performance?
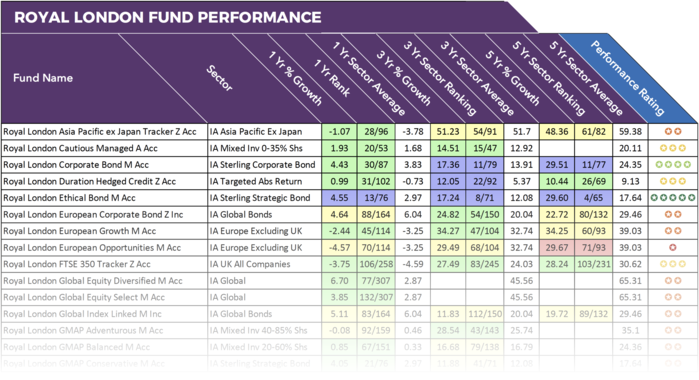
Ah, the million-dollar question. Royal London’s funds have historically done solid, not spectacular—like a dependable friend who always arrives on time but never brings snacks. Their “Balanced” fund, for example, has returned around 5–7% annually over the long haul. Not bad for a snooze-fiesta, right? But remember: past performance is not a guarantee. That’s finance-ese for “your results may vary, and don’t blame me if your cat loses its collar.”
They offer a managed portfolio service, too. So if you’re too busy binge-watching shows or perfecting your sourdough starter, they’ll pick the investments for you. It’s like having a personal chef for your money, but without the apron.
The Pros and Cons (Because Nothing’s Perfect)
Pros: Low fees, ethical focus, low minimum investment, and a calm, trustworthy vibe. Also, their app is surprisingly easy to use. No, seriously—it doesn’t look like it was designed by a drunk spider. You can check your balance, top up, and even change your risk level while waiting for the kettle to boil.
Cons: Their investment choices aren’t as vast as, say, Vanguard or Hargreaves Lansdown. If you’re a trading ninja who wants to buy stocks in Dogecoin or Tesla, this isn’t your dojo. Royal London is more “slow and steady wins the race” than “yolo, lambo, baby.” Also, their customer service can be a bit slow—like a tortoise on sedatives. But they always get there.
Who Is This ISA For?
It’s perfect for the patient, slightly lazy investor who wants to set and forget. You know, the kind of person who waters their cactus once a year and it still thrives. If you’re a busy bee with a 9-to-5, a side hustle, and a life, Royal London does the heavy lifting. It’s for ethical investors who care about the planet but also want their pension pot to look plump.

If you’re a day trader who checks stocks every ten minutes while hiding in the loo at work, this might bore you to tears. But boredom isn’t always bad—sometimes it’s just safe.
The Verdict (Drumroll, Please)
Royal London’s Stocks and Shares ISA is like a comfortable pair of slippers: not flashy, but it keeps your toes warm and your feet happy. It’s reliable, ethical, and won’t eat your savings in fees. For beginners or anyone who sleeps better knowing their money isn’t funding evil stuff, it’s a solid choice.
Is it the best ISA ever? No, but it’s like the third-best biscuit in the tin—you’re still thrilled to eat it, and you’ll reach for it again. Just remember: investing is a marathon, not a sprint. You don’t win by popping champagne at the starting line; you win by crossing the finish line with a chubby account.
So go ahead, open that ISA. Give your money a job. Let it work 9-to-5 while you sleep. And one day, you’ll wake up, check your phone, and smile. Because that little £25 a month? It’s now a whole pile of happiness, tax-free. You’ve got this.
Now go treat yourself to that curry. You’ve earned it.