
What Happens With Pension When Someone Dies

When someone passes away, the last thing anyone wants to do is drown in paperwork. But somewhere between the funeral sandwich platters and the distant cousin asking about the china, you’ll hear it: “What happens to the pension?” It’s the financial version of a ghost story—everyone has a theory, but nobody really knows the ending.
Think of a pension like a very loyal, slightly boring robot. It spent decades collecting small bits of money for you, humming along in the background. The robot’s only job was to pay you a set amount every month, no matter how many times the stock market sneezes. But when the owner passes away, that robot doesn’t just shut off. It waits for new instructions.
The first thing to understand is that it depends on the type of pension. Most people have a state pension (the one the government gives you for paying taxes), and many have a private or workplace pension (the one you maybe matched with your employer because you are financially savvy). Treat them like two different flavors of ice cream—they melt at different speeds and have very different rules.
Must Read
- Did Kelly Clarkson Just Get Julia Roberts Treatment? The Untold Truth Behind Brooklyn’s $15m Animatronic Bird Drama
- The 5-minute Visit That Broke The Internet: How Kelly Clarkson Sparked A $15 Million Mechanical Bird War
- Petty Revenge Or Viral Genius? Brooklyn Store Slaps $15,000,000 Tag On Molly The Bird After Kelly Clarkson Backlash
The State Pension: The One That Blinks Twice and Disappears
For the state pension in most countries, the rules are surprisingly blunt. When a single person dies, the state pension basically stops. It’s like a subscription you forgot to cancel—it just ends. Your spouse or partner doesn’t automatically get to keep your full state pension check.
However, there is a small, complicated loophole called the “inherited state pension.” This usually only exists for married couples or civil partners, and even then, it’s a partial amount. It’s like you ordered a pizza and your partner gets to keep one slice. It’s something, but you’re not having a party.
The government isn't being cruel here; they designed the state pension as a personal income for life. As soon as life ends, the payments vanish. It’s the financial equivalent of a magician’s disappearing act, except nobody is applauding and you’re left holding an empty hat.
Private and Workplace Pensions: The Plot Thickens
Private pensions are a whole different beast. They are much more generous but also more confusing. Think of them as a treasure chest that has a special key. The key depends on when your loved one retired and what they signed thirty years ago.
The biggest factor is the survivor’s benefit. Many workplace pensions let the retiree choose: “Do you want a bigger monthly check for just you, or a smaller monthly check that keeps paying your spouse after you’re gone?” It’s the classic burger versus salad dilemma of retirement planning.
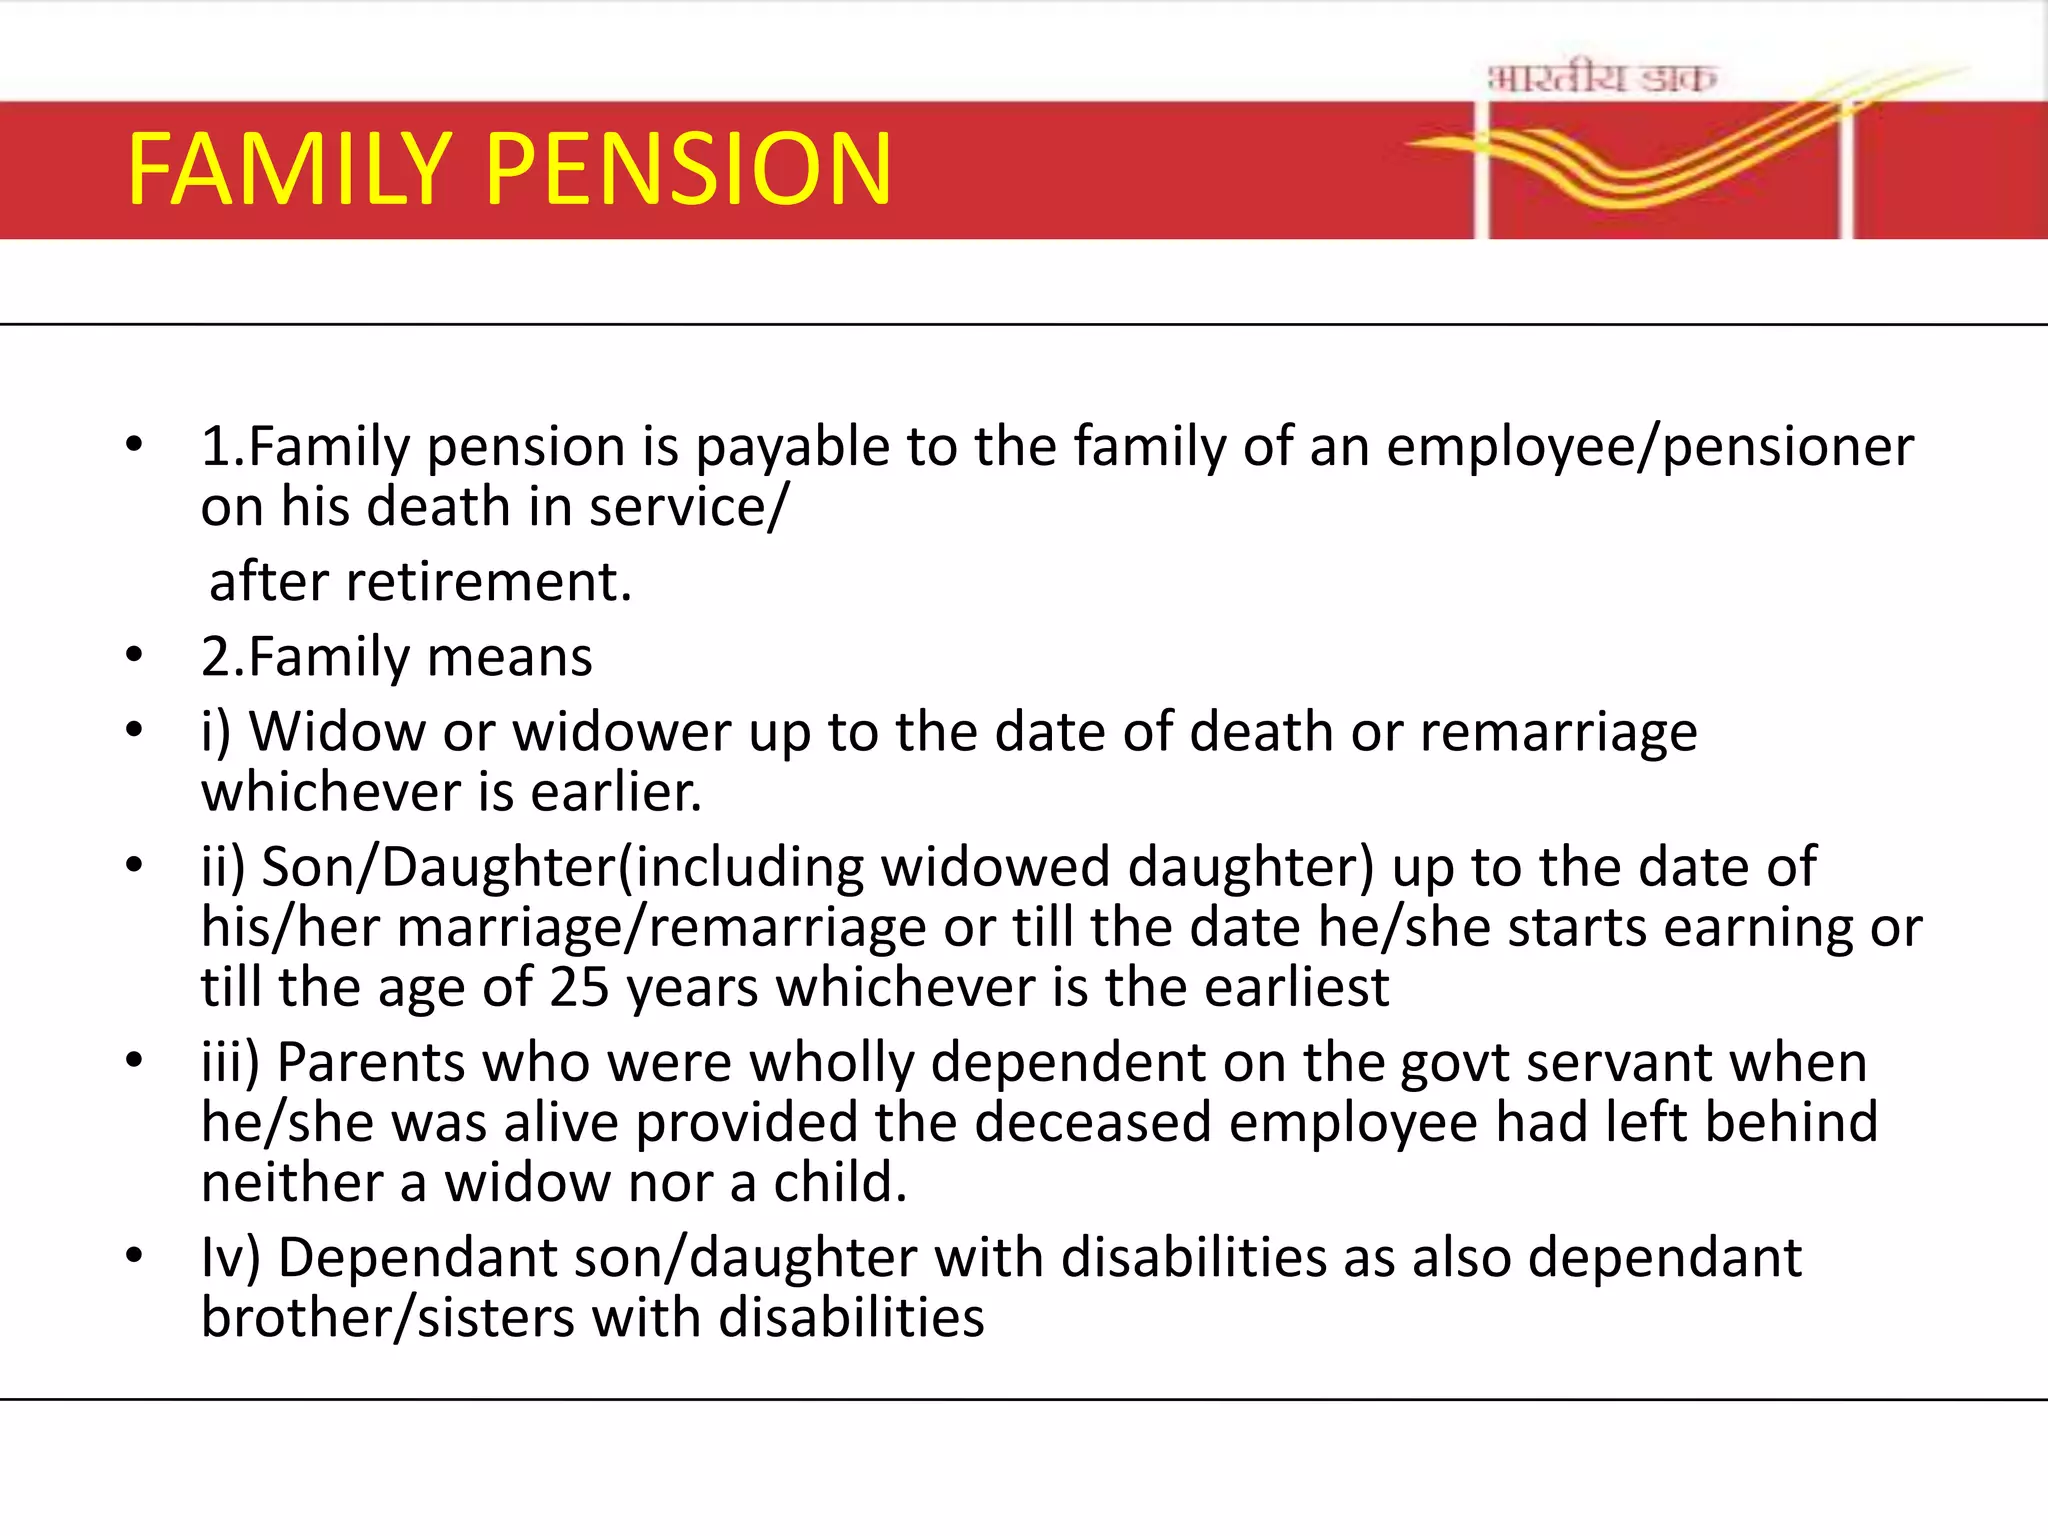
If they chose the “survivor option,” then the pension keeps paying a percentage—usually 50% or 66%—to the surviving spouse for the rest of their life. If they took the “single life option” for a higher payout, the pension dies with them. Poof. Gone. The surviving spouse is left wondering why the robot suddenly took a vacation to the great beyond.
The Lump Sum Surprise
Here’s something that makes people smile: many private pensions also include a death-in-service benefit or a small lump sum. Even if the person was already retired, the pension pot might have a tiny leftover. This is often paid out tax-free to a named beneficiary. It’s like finding a $20 bill in a coat pocket you haven’t worn since 1998.
For those still working, the death benefit can be enormous. Many work pensions pay out two to four times the employee’s annual salary. So if Uncle Bob was earning $60,000, his beneficiaries might suddenly get $180,000. It’s a sad reason to get money, but it often pays off the mortgage or keeps the kids from fighting over a used sofa.
The Spouse’s Dilemma: A Taxing Comedy
Now here is where the funny part starts. If the surviving spouse needs that pension money to live on, they often get a tax bill they didn’t see coming. Pensions are taxed as income. So if you inherit a pension that pays out $1,500 a month, you suddenly owe income tax on it.
It’s like being handed a winning lottery ticket that also comes with a bill for the “pleasure of winning.” You nod, smile, and say “thank you,” while secretly wondering if the deceased had a secret agenda against your annual vacation fund.
The “Beneficiary Blunder”
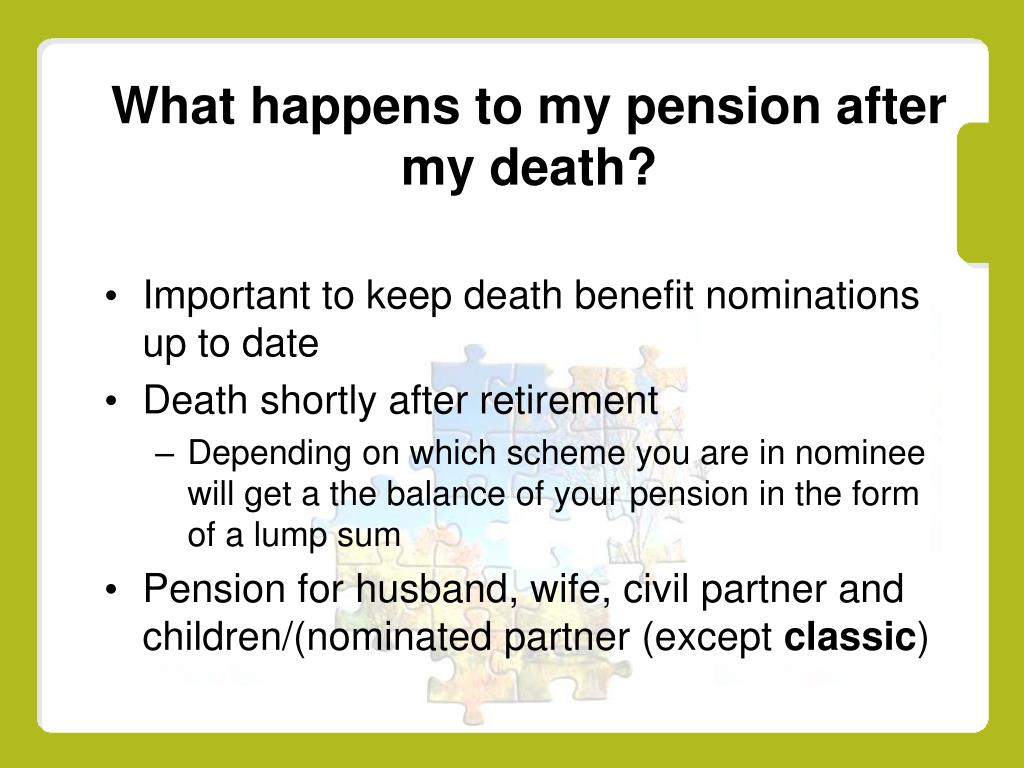
Here is a true-life anecdote that will make you snort. My neighbor’s father passed away. He had a small pension from a job he worked at for ten years. He’d told everyone, “It’ll go to my wife.” When my neighbor called the pension company, they said, “Sorry, sir, the named beneficiary is his college roommate from 1972.” Nobody had updated the form in forty years!
So his father’s pension—all $18,000 of it—went to a man in Florida who my neighbor didn’t even recognize from family photos. The moral of the story: check your beneficiary forms every five years, or you might accidentally gift your retirement savings to someone who smells like old beer and regret.
The Final Nod
If you are dealing with a deceased loved one’s pension, take a deep breath. Don’t panic. Call the pension provider, but expect to be put on hold for thirty minutes while listening to “Greensleeves” on a synthesizer. You’ll need their date of birth, death certificate, social security number, and possibly a sample of their handwriting from 1985.
In the end, the pension usually does one of three things: stops completely, continues at a reduced rate to a spouse, or pays a lump sum. It’s rarely a windfall, but it’s also rarely nothing. Think of it as the last financial hug from someone who tried to be responsible.
So the next time you hear “what happens to the pension,” just nod wisely. Know that the robot might keep working for a bit, or it might clock out forever. Either way, life goes on, and you’ll probably need more coffee and a very detailed list of phone numbers. And maybe—just maybe—you’ll remember to update your own beneficiary form before you accidentally fund a strange man’s retirement in Florida.