
When Is The Best Time To Renew Car Insurance

Alright, let’s talk about car insurance renewal. It’s one of those grown-up chores that feels about as fun as folding a fitted sheet. But trust me, knowing the best time to do it can save you real cash and a headache or two.
First things first: your renewal date is a trap. Insurers love to send you that letter a few weeks before, hoping you’ll just nod and click “renew” without thinking. Don’t fall for it. That’s like buying the first pair of jeans you try on—you might get lucky, but you’re probably overpaying.
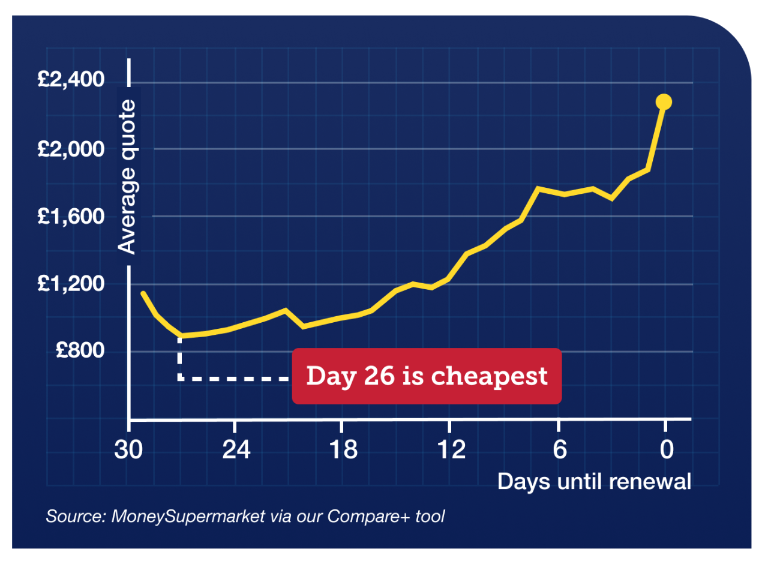
The Golden Window: 21 to 26 Days Before Your Policy Ends
Here’s the juicy secret: the sweet spot for shopping around is about three to four weeks (21–26 days) before your current policy expires. Why? Because insurance companies start getting nervous that you’ll leave them, so they throw you better offers.
Must Read
- Did Kelly Clarkson Just Get Julia Roberts Treatment? The Untold Truth Behind Brooklyn’s $15m Animatronic Bird Drama
- The 5-minute Visit That Broke The Internet: How Kelly Clarkson Sparked A $15 Million Mechanical Bird War
- Petty Revenge Or Viral Genius? Brooklyn Store Slaps $15,000,000 Tag On Molly The Bird After Kelly Clarkson Backlash
Wait too long—say, less than seven days before renewal—and you’re stuck in a high-risk zone. Insurers think you’re desperate, and desperate people pay more. It’s like waiting until the last minute to book a flight; the prices only go up.
But what if you miss the window? Don’t panic.
If you’re reading this and your policy ends next week, just hit renew with your current insurer. Then set a calendar reminder to shop around immediately for the next month. You can often switch mid-policy and get a pro-rated refund.
Pro tip: Avoid renewing on a Friday afternoon when you’re tired and just want to go home. That’s when you click “yes” to add-ons like “key replacement for a magic car that doesn’t exist.” Take it from someone who once bought “accidental strawberry-ice-cream coverage”… joke, but you get the point.
Seasonal Timing: The Sneaky Best Months to Renew
Believe it or not, the time of year matters. Studies show that December and January are often the cheapest months to buy a new policy. Why? Because fewer people are buying cars or driving, so insurers lower rates.
On the flip side, summer (especially July and August) tends to be pricier. More young drivers, more road trips, more… questionable decisions in convertibles. If you can, plan your renewal to land in the off-season.
Weekday vs. Weekend: Yes, It’s a Thing
Want to save a bit more? Aim to shop for quotes on a Tuesday or Wednesday. Insurers run new data batches mid-week, and rates can dip slightly. Sunday night? That’s when everyone else is panic-shopping, so prices often creep up.
Think of it like grocery shopping: Tuesday morning at 10 a.m. is peaceful. Sunday at 5 p.m. is chaos where you end up buying weird-flavored chips. Same applies to insurance shopping.
The Big No-No: Don’t Let Your Policy Lapse
I know, I know—life gets busy. But letting your coverage lapse even for one single day is like telling insurers, “Hey, I’m a risk!” They’ll jack up your rates by as much as 30%. That’s worse than forgetting to water a plant; the plant dies and your wallet does too.
If you’re between cars or selling yours, buy a non-owner policy. It’s cheap, keeps your history “active,” and stops rate hikes. It’s like keeping a gym membership just to avoid the reactivation fee.
What About Bundling? (The Tempting Trap)
Sure, bundling home and auto can save you money—but only if you actually shop the bundle. Insurers love to say, “You’ll save 20% by bundling,” while quietly raising your base rates. Always get three to five quotes for the bundle and for standalone policies.
Oh, and if you’re a new driver (or a teenager’s parent), renew three months before your 25th birthday. Once you hit 25, rates often drop. But if you renew after your birthday, the discount might not kick in until the next cycle.
The Ultimate Checklist for Timing Your Renewal
Here’s your action plan, wrapped in a neat little bow:
1. Mark your calendar 26 days before expiry. This is your “start shopping” day. Do not skip it.
2. Compare at least three quotes. Use comparison sites, but also call one local insurer. Local guys sometimes have secret discounts for good drivers.

3. Check for life changes. Moved? Married? Started working from home? These can lower your rate. Insurers don’t tell you this—they’re like mimes, silent and mysterious.
4. Renew 14 to 21 days before expiry. This locks in a good rate without the stress of a last-minute scramble.
What If You Find a Better Deal After Renewing?
You can still switch! Cancel your new policy within the “free look” period (usually 14–30 days). You’ll get a full refund, no questions asked. It’s like the insurance version of a regret-free return policy—but without the awkward receipt.
Just make sure you have the new policy start before the old one ends. Overlap is fine; a gap is not. Think of it like a baton relay: don’t drop the baton of coverage.
The Fun Twist: Reward Yourself for Being a Smart Cookie
Here’s the uplifting part: once you’ve nailed your renewal timing, you’ve basically earned yourself a small financial victory. You saved money by being clever, not by cutting corners. Pat yourself on the back—then spend that saved cash on something fun, like a fancy coffee or a new car air freshener that smells like “Dreams and Confidence.”
Remember: your car insurance renewal is not a chore—it’s a treasure hunt. The treasure? More money in your pocket and the smug satisfaction of outsmarting the system. And if you mess up the timing? No big deal. There’s always next year, and now you know the secret.
So go ahead, set that calendar reminder, click those quotes, and renew with a grin. You’ve got this—and your car will feel cooler knowing it’s insured by a genius like you. Drive safe, save hard, and may your rates always be low.