
Cheapest Car To Insure For A New Driver
So, you’ve just passed your test. Congratulations! That mix of terror and euphoria is completely normal. But now, the real fun begins: finding a car that won’t bankrupt you before you even pull out of the driveway.
Let’s be honest, insurance for new drivers is basically a rite of passage. It feels like the universe is asking you to pay for a small yacht every month. But it doesn’t have to be that way—if you pick the right chariot.
Why Your Choice Matters More Than You Think
Think of insurance companies as really nervous older siblings. They look at a new driver and see risk. To them, you’re a human pinball machine with a learner’s permit.
Must Read
- Did Kelly Clarkson Just Get Julia Roberts Treatment? The Untold Truth Behind Brooklyn’s $15m Animatronic Bird Drama
- The 5-minute Visit That Broke The Internet: How Kelly Clarkson Sparked A $15 Million Mechanical Bird War
- Petty Revenge Or Viral Genius? Brooklyn Store Slaps $15,000,000 Tag On Molly The Bird After Kelly Clarkson Backlash
They don’t care if you’re a careful driver. They care about accident statistics, repair costs, and how fast your car can go from zero to “oops.” The car you choose is the single biggest factor in your premium.
Picking a cheap-to-insure car is like choosing a loyal golden retriever over a hyperactive cheetah. One is forgiving, safe, and cheap to feed. The other is exciting but will cost you a fortune in vet bills and speeding tickets.
The Holy Grail: Small, Safe, and Boring (In a Good Way)
Remember that old hatchback your friend’s mom drove? The one that smelled faintly of coffee and had a cassette player? That car is your new best friend.
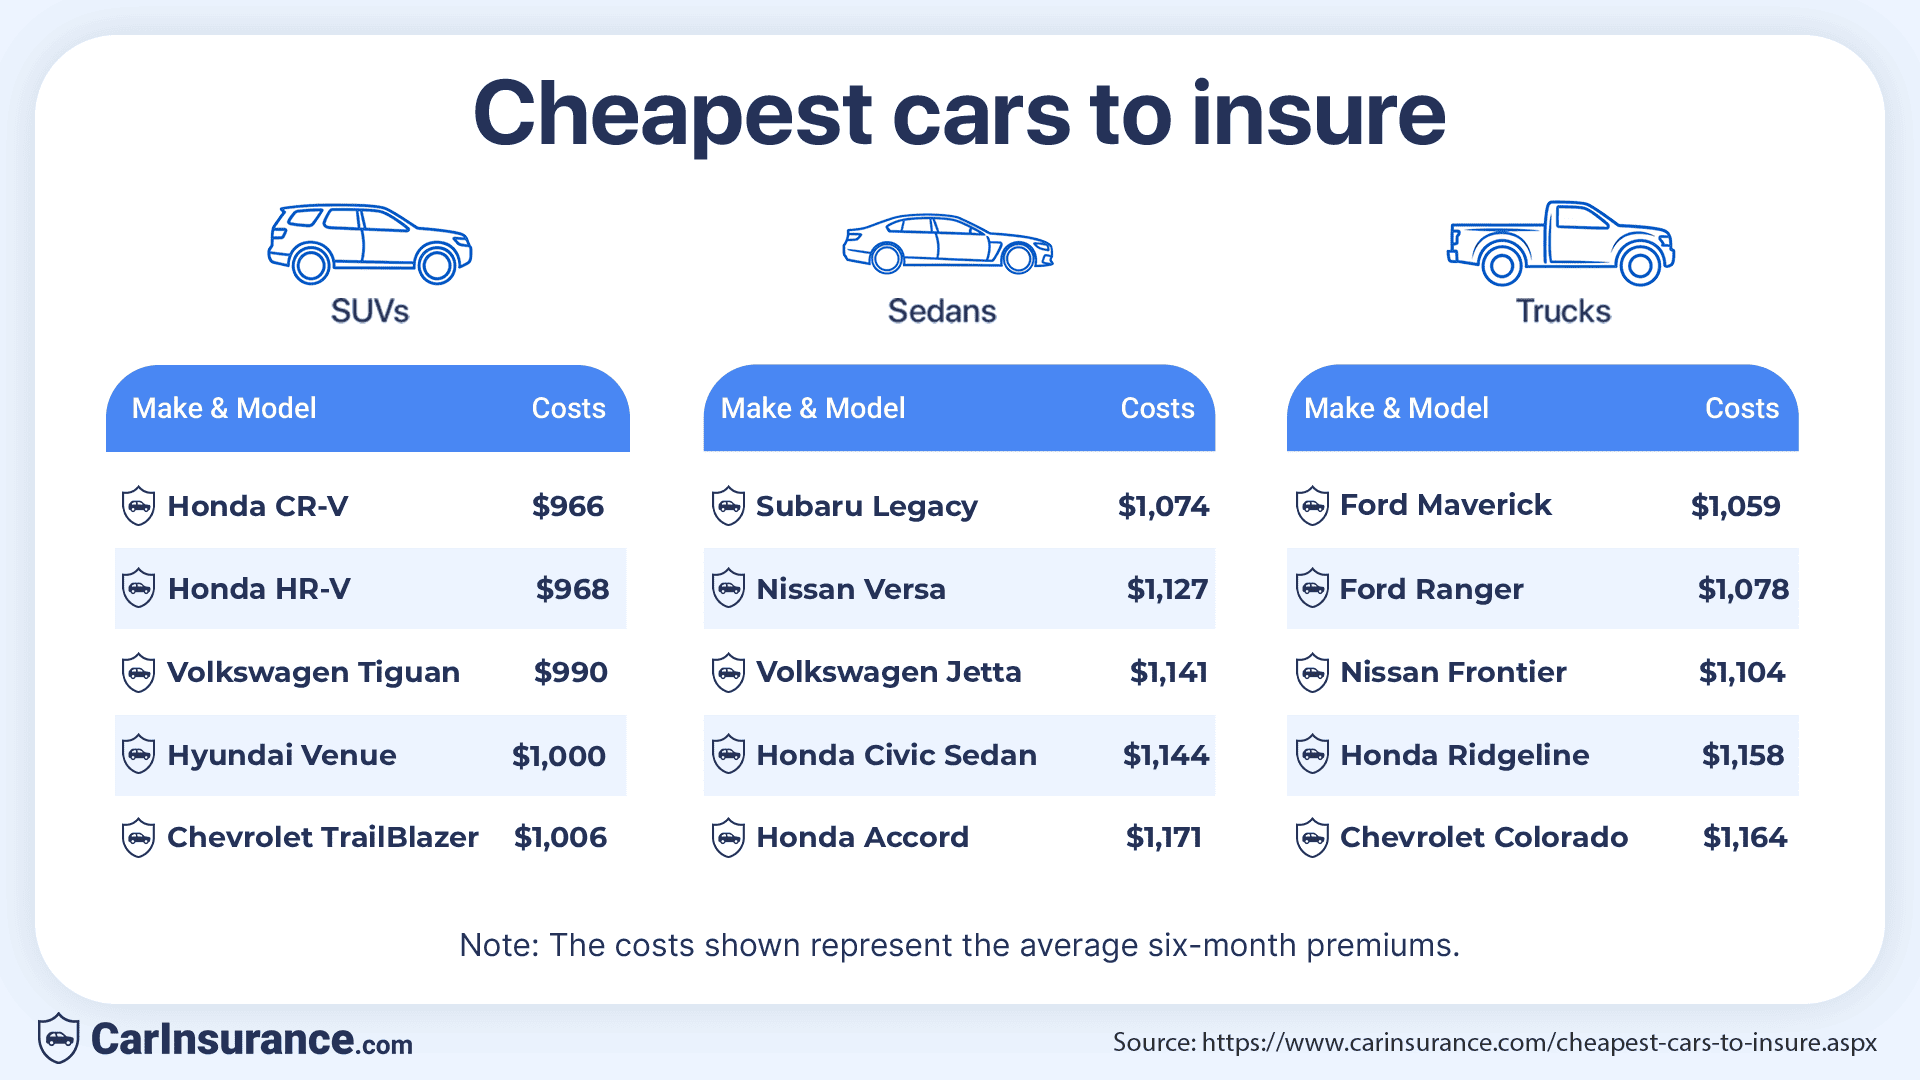
Cars like the Honda Fit, Mazda 2, or Hyundai Elantra are the unsung heroes of the insurance world. They aren’t flashy, but they are cheap to fix, hard to steal, and have excellent safety ratings.
Do you want to impress your friends with a loud engine? Or do you want to have an extra $150 in your pocket every month to spend on tacos? The choice is yours.
The Reliable Station Wagon (Yes, Seriously)
Okay, I know “station wagon” sounds like something your dad listened to on vinyl. But hear me out. A Subaru Outback or a Toyota Corolla Wagon is an insurance goldmine.
These cars say, “I am a responsible person who plans picnics and carries gardening supplies.” Insurers love that vibe. They practically hand you a discount for being so sensible.
Plus, you can actually fit all your friends and their snacks inside. Being boring has never felt so practical.
The Cars to Avoid (Unless You Love Paying Rent to an Insurance Company)
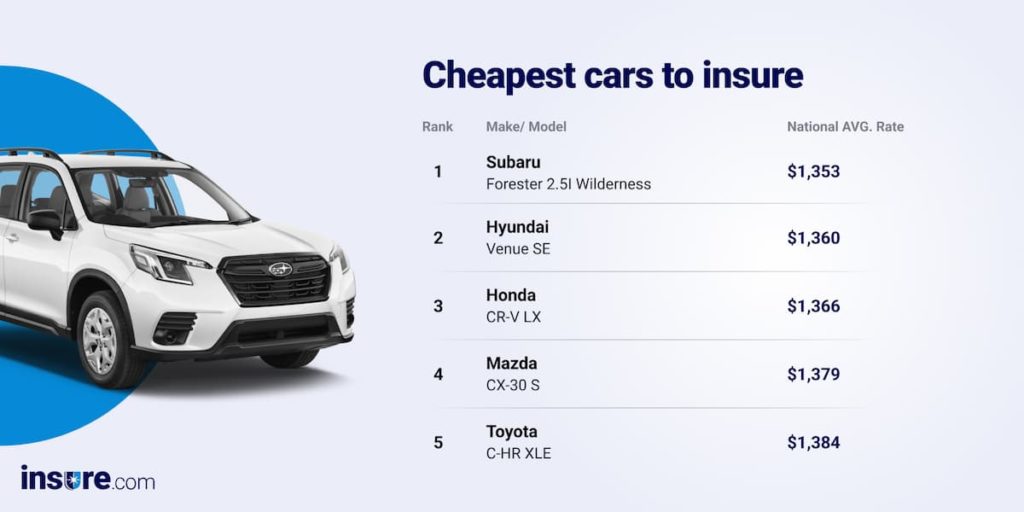
Please, for the love of your wallet, do not buy a two-door coupe as your first car. A Ford Mustang or a Chevrolet Camaro might look cool in the parking lot, but your insurance broker will laugh at you.
These cars are magnets for speeding tickets and are often targeted by thieves. Insurers see them and think, “Teenage speed demon.” Your premium will be higher than your car payment.
Also, avoid anything with a turbo, a V8 engine, or the word “sport” in the name. Save the fun car for when you’re thirty and have a retirement fund.
The Electric Surprise
Here’s a plot twist: some electric cars are actually cheaper to insure for new drivers. Look at the Nissan Leaf or a Chevy Bolt.
They are slow, quiet, and have excellent safety features. They also have zero street-racer reputation. Your insurance company will think you are a tree-hugging tax accountant.
And you can drive in the carpool lane. That’s a win for the planet and your monthly budget.
Real Life Example: Pizza vs. Premiums
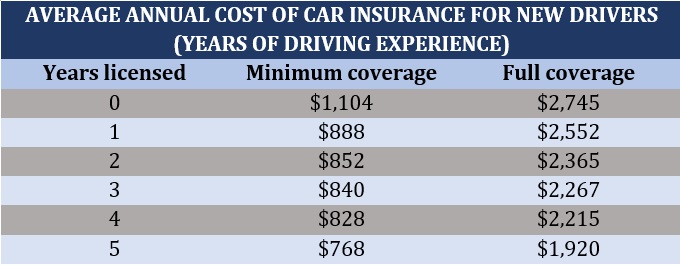
Let me paint you a picture. My cousin, Liam, bought a flashy Mitsubishi Lancer right after he passed his test. He spent $300 a month on insurance. He could only afford to eat instant noodles.
My other friend, Sarah, bought a used Hyundai Accent. Her insurance was $95 a month. She went out for pizza every Friday night and still saved for a trip to the beach.
Who do you want to be? Noodle-Liam or Pizza-Sarah? I thought so. Choose the car that says “I like having fun money,” not “I like looking rich while eating ramen.”
A Few Final Tricks to Save Even More
First, buy a used car. A brand new car costs more to insure because it’s worth more to fix. A five-year-old reliable hatchback is a financial miracle.
Second, check if your parents have a good driver discount you can share. Some insurers let you piggyback on their clean driving record for a small fee. It’s like borrowing their good reputation.
Third, never, ever lie about your mileage or where you park. Insurers are like tech-savvy detectives. They will find out, and then your rates will really hurt.
Your Starter Checklist
Before you buy, call three insurance companies and ask for a quote. Give them the exact make and model you’re looking at. This takes ten minutes and could save you thousands.
Look for cars with a small engine (1.0 to 1.6 liters), four doors, and a great safety rating. The Honda Civic and Volkswagen Golf are also solid bets if you can find an older model.
Remember, your first car isn’t a status symbol. It’s a tool to get you to your job, your friends’ houses, and the drive-thru. Make it a cheap tool, and you’ll enjoy the ride a lot more.
So go ahead. Embrace the boring hatchback. Drive a car that says “I’m sensible.” And laugh all the way to the bank—with a slice of pizza in your hand.