
What Happen To Your Pension When You Die
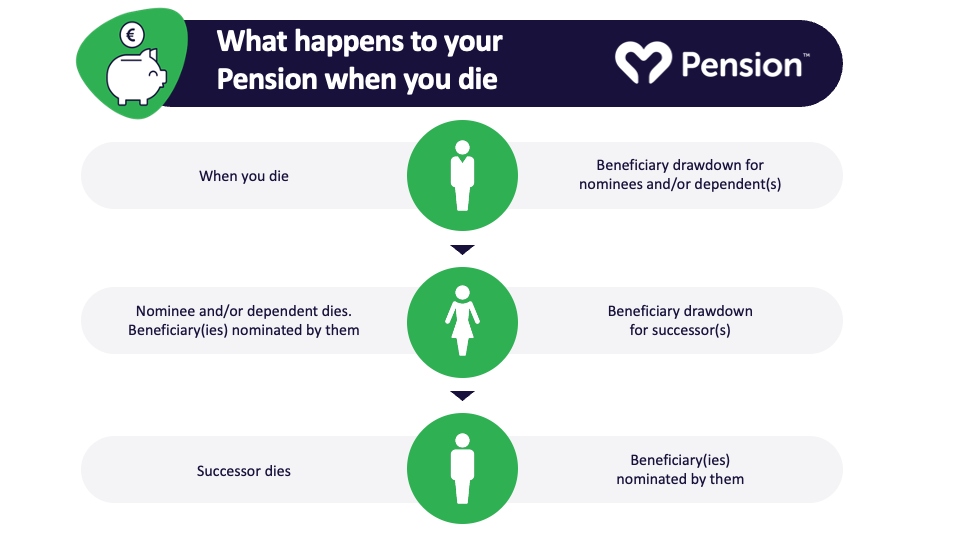
So, you’ve been squirreling away money into a pension for decades, dreaming of retirement—beach chairs, bad golf shorts, and early-bird specials. But then, the grim reaper taps you on the shoulder. What happens to all that cash you saved? Does it just evaporate into the ether like a bad magic trick? Relax, grab a coffee, and let’s unravel this mystery before your executor has a heart attack.
The Great Pension Divide: Defined Benefit vs. Defined Contribution
First, we need to talk about which flavor of pension you have, because your death treats them very differently. Think of it like this: a Defined Benefit pension is a grumpy old cat—it promises you a steady stream of fish (money) for life, but once you die, the cat might stop purring. A Defined Contribution (like a 401k or a personal pot) is more like a bucket of cash with your name on it—whoever you leave the bucket to gets to drink from it.
If you have the old-school "final salary" pension (the grumpy cat), your monthly payments usually stop when you die. Surprise! The pension plan isn't a charity for your heirs—it's a deal for you. Unless you picked a survivor benefit, your spouse might get a reduced payment, but your freeloading nephew? He’s getting zero.
Must Read
- Did Kelly Clarkson Just Get Julia Roberts Treatment? The Untold Truth Behind Brooklyn’s $15m Animatronic Bird Drama
- The 5-minute Visit That Broke The Internet: How Kelly Clarkson Sparked A $15 Million Mechanical Bird War
- Petty Revenge Or Viral Genius? Brooklyn Store Slaps $15,000,000 Tag On Molly The Bird After Kelly Clarkson Backlash
The "Joint Life" Option: Your Spouse Gets a Crumpled Coupon
Here’s where it gets juicy. Many pensions let you take a lower monthly payment now, so your spouse gets something after you’re gone. It’s called a joint and survivor annuity. You take a haircut on your own income—sometimes 10% or 20% less—so your partner gets 50% to 100% of your payment for life. It’s like saying, “Honey, I love you, but I’m going to die first, so here’s half my sandwich.”
The hilarious catch? If you die before your spouse, they get that money. But if they die first? You just paid for a benefit you’ll never use. It’s like buying a fire extinguisher for a house that never catches fire—fiscally responsible, but slightly annoying.
Defined Contribution Plans: The Bucket O' Cash
Now, for the 401ks, IRAs, and all those modern pots of gold: you own the bucket. When you die, that bucket goes to your named beneficiary—your spouse, your kids, or even your cat if you put it in writing (though the cat can’t sign a check). This is the good news: the government doesn’t just vacuum it up.
But wait—there’s a tax twist. If your beneficiary is your spouse, they can roll the money into their own retirement account, tax-deferred, and pretend you never died. If it’s anyone else (like your darling child), they have to drain the account within 10 years under the SECURE Act. That means they’ll pay income tax on the withdrawals, possibly a huge bill if they inherit a massive pile.
Surprising fact: 80% of workers forget to update their beneficiary forms after a divorce. Your ex-spouse could end up with your pension while your current partner gets nothing. That’s a plot twist worthy of a soap opera—and a lawyer’s dream.
The "State Pension" Trap: The Government’s Frugal Cousin
What about Social Security (or the state pension, for our UK friends)? That’s a whole different beast. In the US, if you die, your spouse can claim a survivor benefit based on your earnings, but it’s usually less than yours was. The kicker? Your kids can get benefits too—but only if they’re under 18 or disabled. No, your 30-year-old son who “just needs a little help” doesn’t qualify, unless you want to argue with the government.
Fun fact: In the UK, if you die before claiming your state pension, your heirs might get a lump sum—but it’s calculated by a formula that seems designed by a committee of gibberish-spewing wizards. It’s often a few thousand pounds, not a windfall.

How to Die with Style (Financially Speaking)
So, how do you avoid your pension becoming a bureaucratic nightmare? Name your beneficiaries now. Don’t assume “my kids” is enough—write their names. And if you have a defined benefit plan, choose the survivor option that makes sense for your relationship. Single and no kids? Take the maximum payout and party like it’s 1999.
Remember, if you die without a will or beneficiary, your pension goes into probate, where lawyers feast on it like vultures at a barbecue. Your heirs will wait months, maybe years, to get a penny. Don’t be that ghost.
Lastly, consider a pension pot to the grave strategy: take your defined contribution money, invest it, and leave the rest to a charity or a loved one. The government hates that because they can’t tax your ghost. But it’s legal, so go ahead—spite them from the afterlife.
In short, your pension doesn’t disappear when you die. It either stops paying, pays your spouse, or lands in a bucket for your heirs. The key? Plan ahead, update your forms, and don’t let your ex get a free ride. Now go enjoy that beach chair—you’ve earned it, even if nobody else will get the balance.