
Which Banks Can Dwp Not Check Online
We’ve all been there, right? You’re checking your bank balance on a lazy Sunday morning, coffee in hand, and you think, “I wonder if anyone else is peeking at this?” For millions of people in the UK, that “anyone” is the Department for Work and Pensions, or DWP. They have the power to check your bank accounts, but here’s the fun part: they can’t check every single bank out there. It’s like a game of hide-and-seek, except the stakes are your benefits and a bit of peace of mind.
The Big Secret: Which Banks Are Off-Limits?
The DWP has a magic list of financial institutions they can automatically access through a system called Real Time Information. But this list is not a complete A-Z of every bank in the land. Think of it like a VIP party; some banks have a bouncer, and others just leave the door wide open. The DWP can check any bank if they have a warrant or strong suspicion, but for routine, automated checks? They’re limited.
Here’s the warm, fuzzy truth: the DWP cannot check online-only or app-based banks as easily as they can check the big High Street names. Banks like Monzo, Starling, Revolut, and Monese are built on different technology. They often don’t play nicely with the DWP’s old-school scanning systems. It’s like trying to fit a square peg in a round hole—frustrating for the Department, but kind of cozy for you.
Must Read
- Did Kelly Clarkson Just Get Julia Roberts Treatment? The Untold Truth Behind Brooklyn’s $15m Animatronic Bird Drama
- The 5-minute Visit That Broke The Internet: How Kelly Clarkson Sparked A $15 Million Mechanical Bird War
- Petty Revenge Or Viral Genius? Brooklyn Store Slaps $15,000,000 Tag On Molly The Bird After Kelly Clarkson Backlash
Why Should You Care? (Spoiler: It’s Not Just About Cheating)
Imagine you’re a pensioner who loves the simplicity of a digital bank, or you’re a young parent managing childcare costs through an app. You’re not hiding anything! But knowing which banks the DWP can’t scan automatically helps you understand your privacy. It’s the difference between having a glass wall in your living room versus a nice, solid brick wall. Some people just prefer the brick wall—even if they have nothing to hide.
Let’s use a fun comparison. Think of your bank account like your kitchen cupboard. The DWP has a master key to check if you have too many biscuits (i.e., undisclosed savings). But with digital-only banks, that key doesn’t fit the lock. They have to ask you nicely, “Hey, can you open the cupboard?” And you can say, “Sure, after I’ve had my tea.” It’s a buffer of time and process that gives you control.
The “Big Five” Are Open Books
If you bank with Lloyds, Barclays, HSBC, NatWest, or Santander, the DWP’s computer systems can routinely ping them. They’re like your chatty neighbour who tells everyone your business. These banks have agreed to automated data-sharing agreements. It’s not that they’re bad—they’re just the usual suspects that the system was built for.
Meanwhile, newer banks like Atom Bank or Chase UK (the digital arm of big finance) often fly under the radar for automated checks. The DWP can still request info manually, but they need a specific reason, like you claiming Universal Credit while buying a yacht. For the average person saving for a rainy day, this means less chance of a random, anxious “bank review” letter.
But Wait—What About Building Societies and Credit Unions?
Remember the old-school building societies, like Nationwide, Yorkshire, or Coventry? They’re a bit of a mixed bag. Nationwide, for instance, is on the DWP’s list, but many smaller credit unions or local building societies are not. They’re often too small or too quirky for the Government’s software. If you use a tiny credit union that meets at the local church hall every Tuesday, the DWP probably can’t check it online. It’s like looking for a needle in a haystack, but the haystack is your friendly neighbour’s savings pot.
The Real-Life Example: Sarah’s Story
Picture Sarah. She works part-time, claims a little Universal Credit, and uses a Monzo card for her daily coffees and bus fares. One day, she gets a letter: “We need to check your bank accounts.” Sarah panics—she’s done nothing wrong! But because Monzo isn’t in the DWP’s regular check system, the request takes an extra week. Because of that delay, Sarah could calmly gather her receipts and explain a small gift from her mum. The extra time saved her a headache. Had she been with Barclays, the DWP would have seen the same transaction in seconds and guessed the worst.

Does This Mean You Can Hide Everything? Nope.
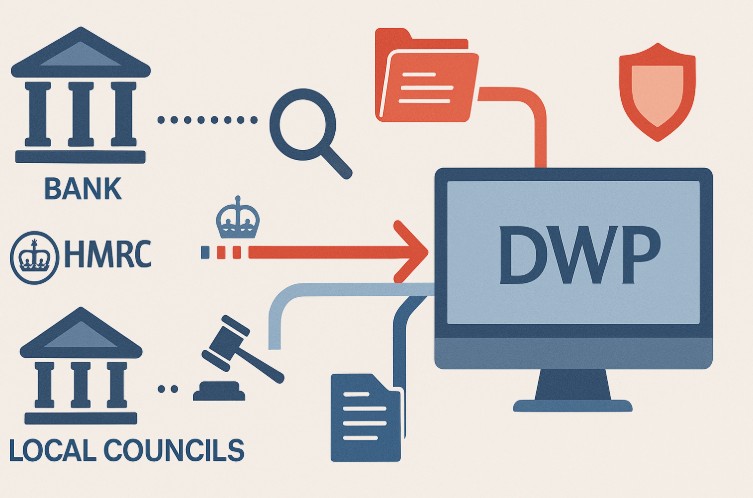
Let’s be real for a second. The DWP can still get your info through court orders, fraud investigations, and tax data from HMRC. They’re not helpless. But for everyday, comfortable living—like keeping a modest savings pot of £6,000 for emergencies—the automated checks are less likely to trigger a flag if you’re with a digital bank. It’s like wearing a camouflage jacket in a forest: you’re not invisible, but you’re harder to spot.
A Gentle Reminder: Honesty Is Still the Best Policy
This article isn’t a cheat sheet for dodging rules. It’s a warm hug for anyone who feels anxious about big brother watching their spending. You don’t have to hide anything, but you do have a right to understand the game. Knowing that the DWP cannot automatically scan Monzo, Starling, Revolut, or smaller credit unions is just smart knowledge—like knowing which shops have the friendliest return policies.
So next time you’re deciding where to park your money, remember: you have choices. Whether you choose a bank that’s transparent like a goldfish bowl or one that’s cosy like a den, the power is in your hands. Stay curious, stay informed, and maybe—just maybe—keep a little digital bank card in your wallet for that feeling of quiet, peaceful control.