
Cars Cheap Insurance For New Drivers
So, you’ve finally got your driver’s license. Congratulations! You’re now legally allowed to navigate the world’s most frustrating parking lots and discover that turn signals are, apparently, optional for other people. But before you hit the road blasting your favorite playlist, there’s one small hurdle: car insurance. And for new drivers, that can feel like trying to buy a pizza with Monopoly money—expensive and slightly ridiculous.
Let’s be real: insurance companies see new drivers like a cat sees a cucumber—terrified and ready to run. You’re statistically more likely to make silly mistakes, like confusing the gas pedal with the brake (we’ve all been there, don’t lie). But here’s the good news: find cheap insurance as a new driver is totally possible. You just need to know the secret handshake—or, you know, follow a few simple tricks.
Why Does Insurance Cost So Much for Newbies?
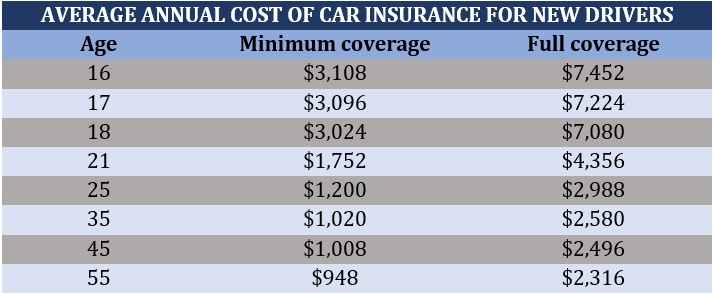
First, let’s understand the enemy. Insurance companies use something called “risk assessment.” Basically, they look at your age, driving history (which is currently a blank slate), and experience level. To them, a new driver is like a toddler with a flamethrower—terrifyingly unpredictable.
Must Read
- Did Kelly Clarkson Just Get Julia Roberts Treatment? The Untold Truth Behind Brooklyn’s $15m Animatronic Bird Drama
- The 5-minute Visit That Broke The Internet: How Kelly Clarkson Sparked A $15 Million Mechanical Bird War
- Petty Revenge Or Viral Genius? Brooklyn Store Slaps $15,000,000 Tag On Molly The Bird After Kelly Clarkson Backlash
They assume you’ll drive at 2 AM for tacos, forget to check your blind spot, or accidentally drift into a cornfield. The result? Sky-high premiums. But don’t panic—you can fight back with strategy and a little bit of shameless begging (metaphorically, of course).
Tip #1: Be a Good Student (Like, Actually)
Did you complete a driver’s education course? If not, do it now. Most insurance companies offer a discount for new drivers who finish an approved program. It’s like telling them, “Hey, I’m not a complete menace; I watched a video about roundabouts!”
Some insurers even offer a “good student discount” if you maintain a B average in school. That’s right—your history report card can save you cash. So, study hard and then use that knowledge to argue with your insurer about rates. It’s the circle of life.
Tip #2: Get Added to a Parent’s Policy (Or a Cool Aunt’s)
This is the ultimate cheat code. If your parents or a guardian have an existing policy, ask to be added as a named driver. It’s like crashing a party where the snacks are already paid for. Their policy will already have a history of safe driving, which makes you look less risky by association.
Just be warned: your parents might ask you to do chores in exchange. But hey, cleaning the garage for a few months is cheaper than paying an extra $1,000 a year. Fair trade.
Tip #3: Drive a Boring Car (Sorry, No Ferrari Yet)
You might dream of a flashy sports car, but insurance companies will charge you more for it than for a small island. Why? Because a fast car equals bigger risk (and bigger repair bills). Instead, choose a used, safe, and boring car—like a Honda Civic or Toyota Corolla. These cars are the insurance equivalent of a plain bagel: basic, reliable, and cheap.
Also, avoid any car with “Turbo” or “GT” in the name. Those letters are basically a siren song for premium hikes.
Tip #4: Compare, Compare, Compare
Never accept the first quote you see. Insurance companies are like bad Tinder dates—they’ll try to get you to settle for the first offer. Instead, use comparison websites to shop around. Get at least five quotes. You’ll probably find a difference of hundreds of dollars for the exact same coverage.
And here’s a pro tip: check for lesser-known insurers. Sometimes the big names charge extra just for their fancy commercials. (Sorry, gecko and emu fans.)
Little Secrets That Save Big Bucks
You can negotiate. Yes, really! Call up an insurance company and ask, “Any discounts for parking in a garage?” or “Do you give a break for anti-theft devices?” They might say no, but sometimes they’ll magically find a discount. It’s like asking for extra fries—you don’t always get them, but when you do, it’s glorious.
Another trick: raise your deductible. That’s the amount you pay out-of-pocket before insurance kicks in. If you raise it from $500 to $1,000, your monthly premium drops significantly. Just don’t crash your car right after, unless you have $1,000 in your sock drawer.
Watch Your Driving Record Like a Hawk
New drivers: every ticket or accident will haunt your insurance rates for years. Avoid speeding, rolling through stop signs, or parking like a maniac. Use a dashcam if you must—it’s like a reality show but for your car. And don’t text and drive. Seriously. Your insurance premiums (and your life) will thank you.
If you do get a ticket, consider taking a defensive driving course. Some insurers will wipe away a first offense if you show you’re trying to improve. It’s like a “get out of jail free” card, but for your wallet.
The Uplifting Conclusion (You Deserve It)
Look, being a new driver is tough. You’re learning to parallel park while dodging potholes and judgmental pedestrians. But finding cheap insurance is absolutely doable—it just takes a little research and a lot of good decisions. You’re not just a statistic; you’re a savvy, budget-savvy driver in training.
One day, you’ll look back at your first insurance policy and laugh. You’ll be older, wiser, and paying half what you do now. And when that happens, you’ll realize that every single payment was worth it for the freedom of the open road—and the ability to drive to a drive-thru at 3 AM for no reason. So go ahead, find that cheap policy, buckle up, and enjoy the ride. You’ve got this.