
Cheapest Time To Renew Car Insurance
Picture this: you’re sitting on your couch, eating a sandwich that’s fighting back, when you get the email. Your car insurance renewal is due, and the premium has mysteriously grown a third arm—and it’s picking your pocket. We’ve all been there, and it feels like your insurance company is trying to fund a private jet.
But here’s the secret most people don’t know: timing is everything. You don’t have to pay the ransom. You just need to know the cheapest time to renew, and it’s weirder than you think.
The Devil’s in the Calendar (and Your Birthday)
First, forget the popular myth that renewal day is a flat, unchangeable trap. It’s not. The cheapest time to renew is not the day your policy ends. That’s the financial equivalent of proposing to someone you just met after three tequilas.
Must Read
- Did Kelly Clarkson Just Get Julia Roberts Treatment? The Untold Truth Behind Brooklyn’s $15m Animatronic Bird Drama
- The 5-minute Visit That Broke The Internet: How Kelly Clarkson Sparked A $15 Million Mechanical Bird War
- Petty Revenge Or Viral Genius? Brooklyn Store Slaps $15,000,000 Tag On Molly The Bird After Kelly Clarkson Backlash
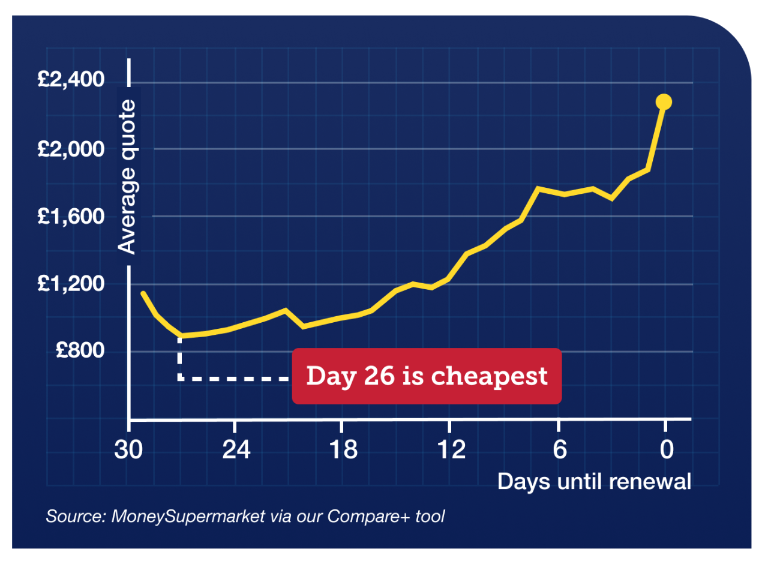
Insurers use something called price elasticity. They know you’re lazy, panicked, and will pay anything to keep driving. Don’t be that person. Your cheapest time is three to four weeks before your renewal date. Why? Because insurers hate empty chairs at the poker table. They’d rather charge you less than lose you to a competitor.
One surprising fact: Wednesdays at 10 a.m. are statistically the cheapest time to buy or renew. I’m not making this up. It’s like finding a unicorn wearing a discount coupon. Nobody shops mid-morning on a hump day, so algorithms drop prices to lure in the few weirdos who do.
The Midnight Magic (And Why You’re Wrong About It)
You’ve probably heard that renewing at midnight on a Tuesday is a hack. Wrong. That’s when bots and desperate insomniacs shop, and prices actually spike. The real sweet spot? Thursday afternoon, between 2 p.m. and 4 p.m. Think of it as the Insurance Happy Hour, minus the stale peanuts.
Here’s the kicker: the cheapest month to renew is January. January is the car insurance version of a clearance rack after Christmas. Everyone’s broke from holiday shopping, so companies slash prices to keep customers. Meanwhile, August is the worst—everyone’s road-tripping, and insurers smell your desperation like sharks smell chum.
The Science of Playing Dumb (But in a Smart Way)
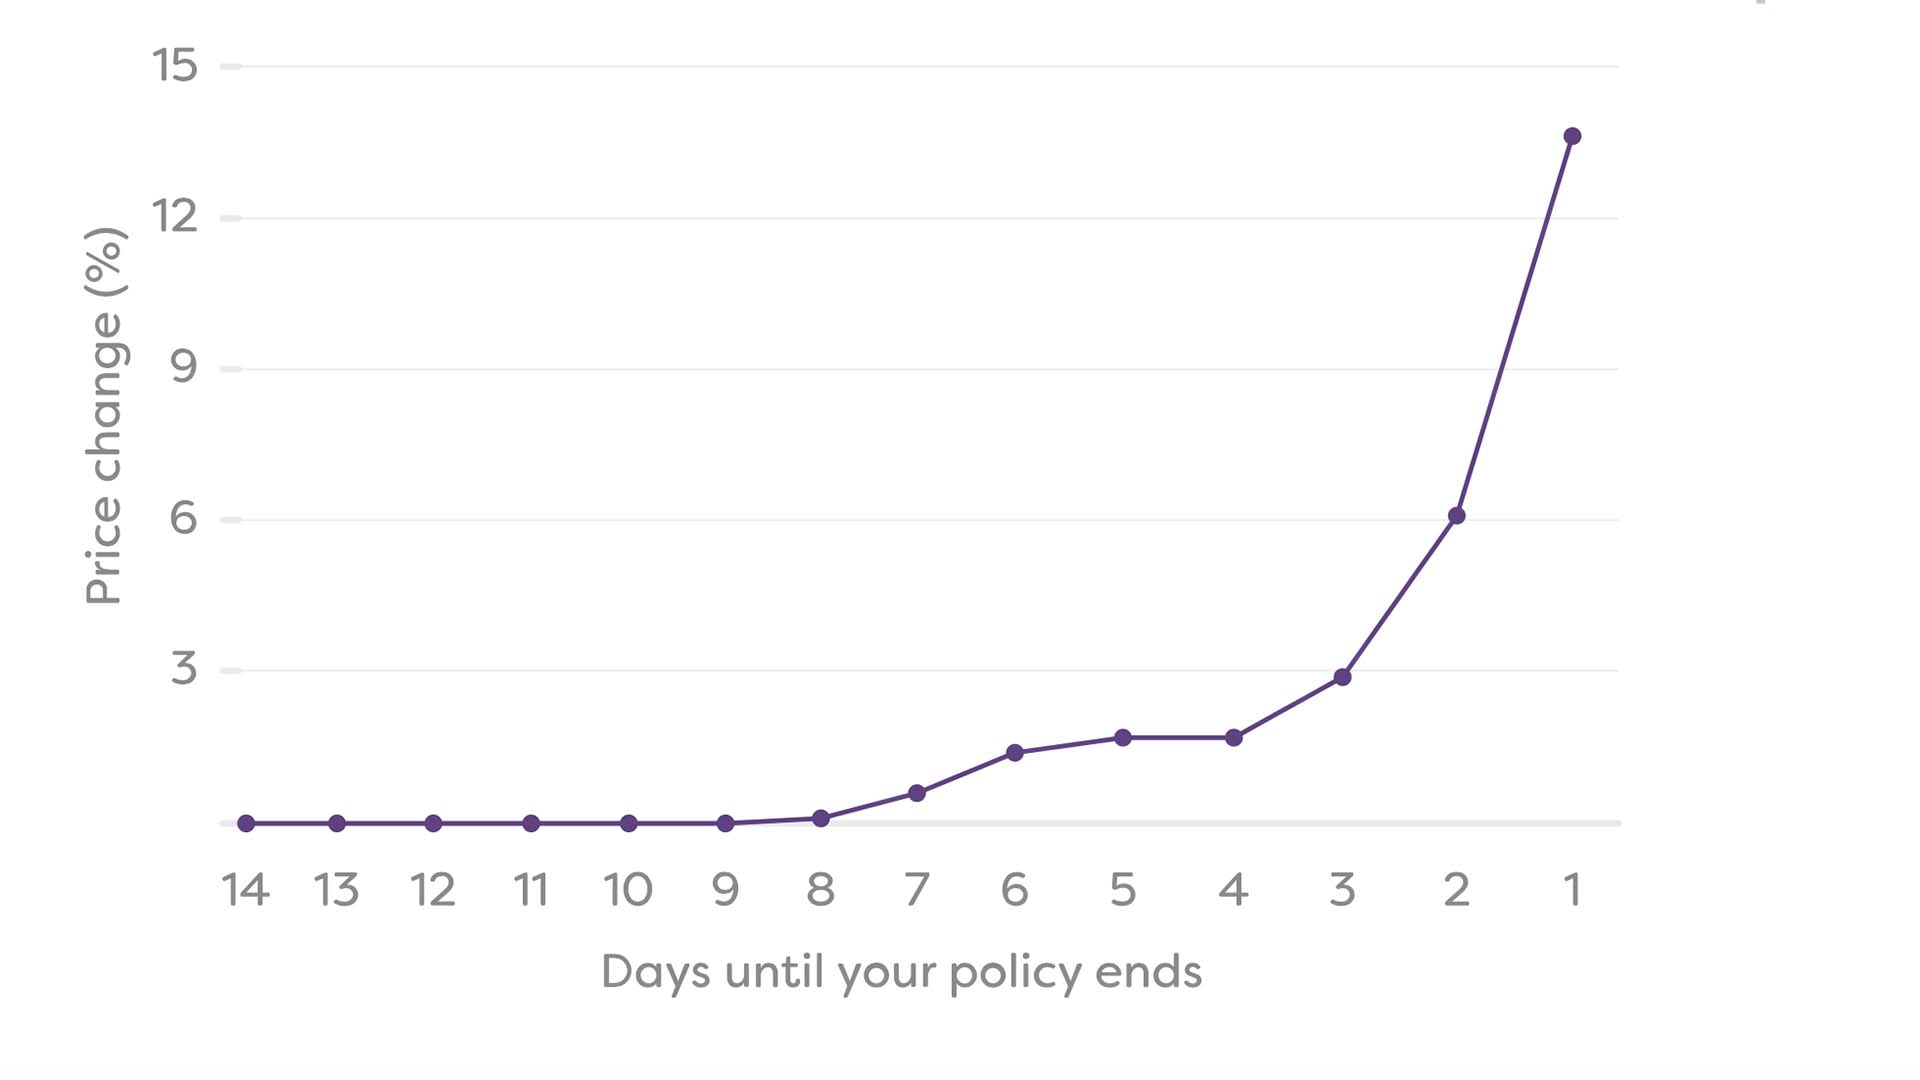
Now, let’s talk about how to time your renewal without losing your mind. You need to be a tiny bit of a manipulative genius. Two words: compare early. Start looking at quotes exactly 26 days before your renewal. Yes, 26 days. Why not 30? Because 26 is when insurers start flicking their “please-don’t-leave-us” switch and dropping prices by up to 10%.
But here’s the joke: after 21 days, those discounts vanish. It’s like a magic trick where the rabbit promptly sues you for animal cruelty. So set a calendar reminder, or use a sticky note on your forehead. Whatever works.
Another bizarre trick: renew on a Tuesday (notWednesday, not Monday). Tuesday mornings see lower rates because underwriters are still recovering from Monday’s misery and haven’t jacked up prices yet. It’s the insurance equivalent of a post-weekend hangover sale.
The Sneaky Seasonal Factor
Did you know that moving your renewal date by two weeks can save you up to $200? Most people don’t. For example, if your policy ends in the middle of hurricane season (June–November), you’re paying extra. If you can push it to December, when storm risk drops, your premium falls like a drunk uncle at a wedding.

One man in Florida famously shifted his renewal to the last week of January and saved $340. He now celebrates “Insurance Day” with a cake shaped like a policy document. I’m not recommending that level of weirdness, but you get the point.
The “Don’t Be an Idiot” Checklist
So, here’s your cheat sheet for the cheapest time to renew: 1) Start 4 weeks early. 2) Shop on a Tuesday morning. 3) Aim for January. 4) Avoid August like it’s your ex’s wedding. And for heaven’s sake, don’t auto-renew without looking. That’s how you end up paying for “accidental fire coverage” on a bicycle.
One final, glorious truth: the cheapest time to renew is actually right after you’ve had a bad day. No, really. Studies show that people who shop for insurance after running a red light or getting a parking ticket are more likely to overpay because they’re desperate. Don’t do that. Wait until you’re calm, fed, and haven’t seen a single piece of bad news.
Now go, my friend. Save your money. And remember: your insurance company doesn’t love you. But a cleverly timed renewal? That’s the closest thing to a financial hug you’ll ever get.