
Premium Bonds Prize Fund Rate Change

So, you’ve heard the news? The Premium Bonds prize fund rate just changed again. And yes, it’s actually a fun topic.
Why? Because it involves money, magic, and a huge dollop of pure, uncut chance. Let’s dive into the madness.
The Big Number: 4.65%... But Wait
The headline rate dropped to 4.65% from 4.75%. That’s the average return for every pound you’ve got stashed away. But here’s the punchline: you will almost certainly not get that.
Must Read
- Did Kelly Clarkson Just Get Julia Roberts Treatment? The Untold Truth Behind Brooklyn’s $15m Animatronic Bird Drama
- The 5-minute Visit That Broke The Internet: How Kelly Clarkson Sparked A $15 Million Mechanical Bird War
- Petty Revenge Or Viral Genius? Brooklyn Store Slaps $15,000,000 Tag On Molly The Bird After Kelly Clarkson Backlash
Premium Bonds don’t pay interest. They pay for dreams. The prize fund is the pool of money that funds all those little wins and the occasional life-changing jackpot.
Think of it like this: the rate dropped because NS&I (the bank) is being a bit more stingy with the party budget. But the party itself? Still on.
The Quirky Math of Winning
Here’s a weird fact: your odds of winning any prize are currently 22,000 to 1 per bond, per month. That sounds terrible, right? But it’s actually the best odds you’ll ever have playing a game of pure luck against a government institution.
And get this: a single bond has a one in 53 billion chance of winning the £1 million jackpot each month. That’s about the same odds as being struck by lightning while winning the lottery. It’s gloriously, absurdly improbable.
But people still buy them. Why? Because it’s fun. It’s the dopamine hit of checking the app and seeing that little green “Winner!” symbol.
The Little Wins Are the Secret Sauce
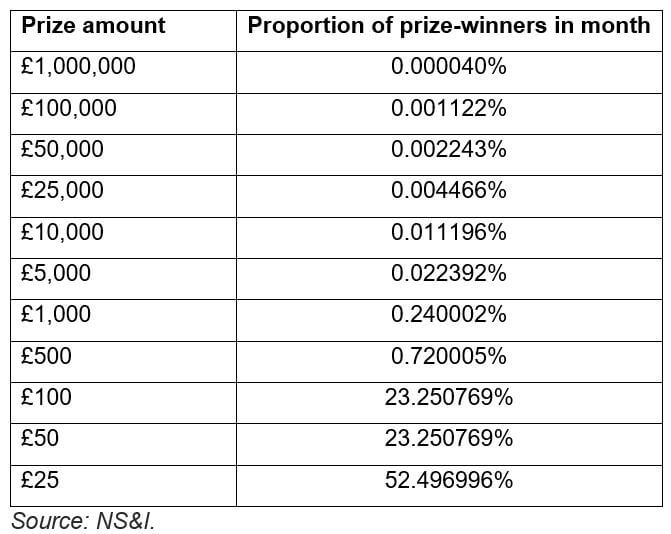
Nobody buys Premium Bonds to get rich slowly. You buy them for the £25 wins. The £50 wins. The occasional £100 that makes you feel like a financial ninja at the supermarket.
Here’s a secret: the new rate means fewer £100 prizes and more £25 prizes. So you’ll win more often, but with less splash. It’s like swapping a champagne cork for a constant stream of soda water. Still bubbly.

And the tax? Zero. Nada. Zilch. That’s a quirky flex no savings account can match. You can win a million quid and keep every penny.
The “Ernie” Factor
Let’s talk about the machine that picks the winners. It’s called Ernie. Yes, an actual name. Ernie stands for “Electronic Random Number Indicator Equipment.”
Ernie is a physical machine that uses quantum randomness to generate numbers. It’s basically a super-powered lava lamp of chance. Every month, Ernie coughs up around 6 million winning bond numbers.
So when the prize fund rate changes, you’re really just tweaking Ernie’s diet. Less food for the giant jackpots, more snacks for the little ones. Ernie doesn’t care. Ernie just rolls the quantum dice.
Should You Care?
If you have less than £1,000 in bonds? Honestly, probably not. The change will feel like a whisper. You might win one fewer £25 prize per decade. Yawn.
If you have £50,000 (the maximum)? Now it’s a real conversation. That 0.1% drop means you’re losing about £50 a year in “expected” winnings. But remember: expected is not real.
The beauty of Premium Bonds is that your capital never goes down. You can cash out anytime, take your money, and walk away. No penalties. No drama. It’s the only “investment” where you can lose nothing but still dream of winning everything.
The Fun Part: The “What If” Game
Here’s why this topic is just plain delightful. Close your eyes. Imagine you have £100 in bonds. One month, Ernie picks your number for £1 million.
Your odds? Terrible. Your excitement? Infinite. That’s the magic. The prize fund rate doesn’t kill that dream—it just gives it a slightly less generous pillow to rest on.
Plus, there’s a weird social currency. You can brag to your friends: “My bonds are paying out 4.65%!” They’ll be impressed. Then you smirk and admit, “Well, I haven’t won anything in two years.”
It’s the only savings product where you can be simultaneously exactly average and completely unlucky at the same time.
The Final Punchline
Should you sell your bonds because of the rate cut? No. Unless you need the cash. The rate change is like a weather forecast for a picnic: useful to know, but you’re still going to eat the sandwiches anyway.
Premium Bonds are not a retirement plan. They’re a happiness subscription. You pay by locking up your cash, and you get a monthly ticket to the lottery of life. The prize fund rate is just the price of that ticket.
So check your bonds. Keep dreaming. And if you win a tenner, buy yourself a coffee and toast to Ernie. He’s doing his best.
Just don’t buy bonds expecting to become a millionaire. Buy them because it’s fun. And honestly, that’s the only rate that truly matters.