
Cost Of Buying A House Uk Calculator

Let’s be honest: the phrase “buying a house” tends to conjure images of you in a crisp estate agent blazer, holding a cappuccino you’ll never finish. The reality is a spreadsheet session in your pyjamas, staring at a cost of buying a house UK calculator like it owes you money. It’s less Grand Designs and more Grand Theft Auto on your bank balance.
But here’s the thing—this humble calculator is actually your best mate. It stops you from that devastating moment when you realise the dream three-bed Victorian costs an extra twenty grand in stamp duty alone. Think of it as the bouncer at the club of homeownership: it checks your ID before you embarrass yourself at the bar.
The Numbers Game (It’s Not Just a Deposit)
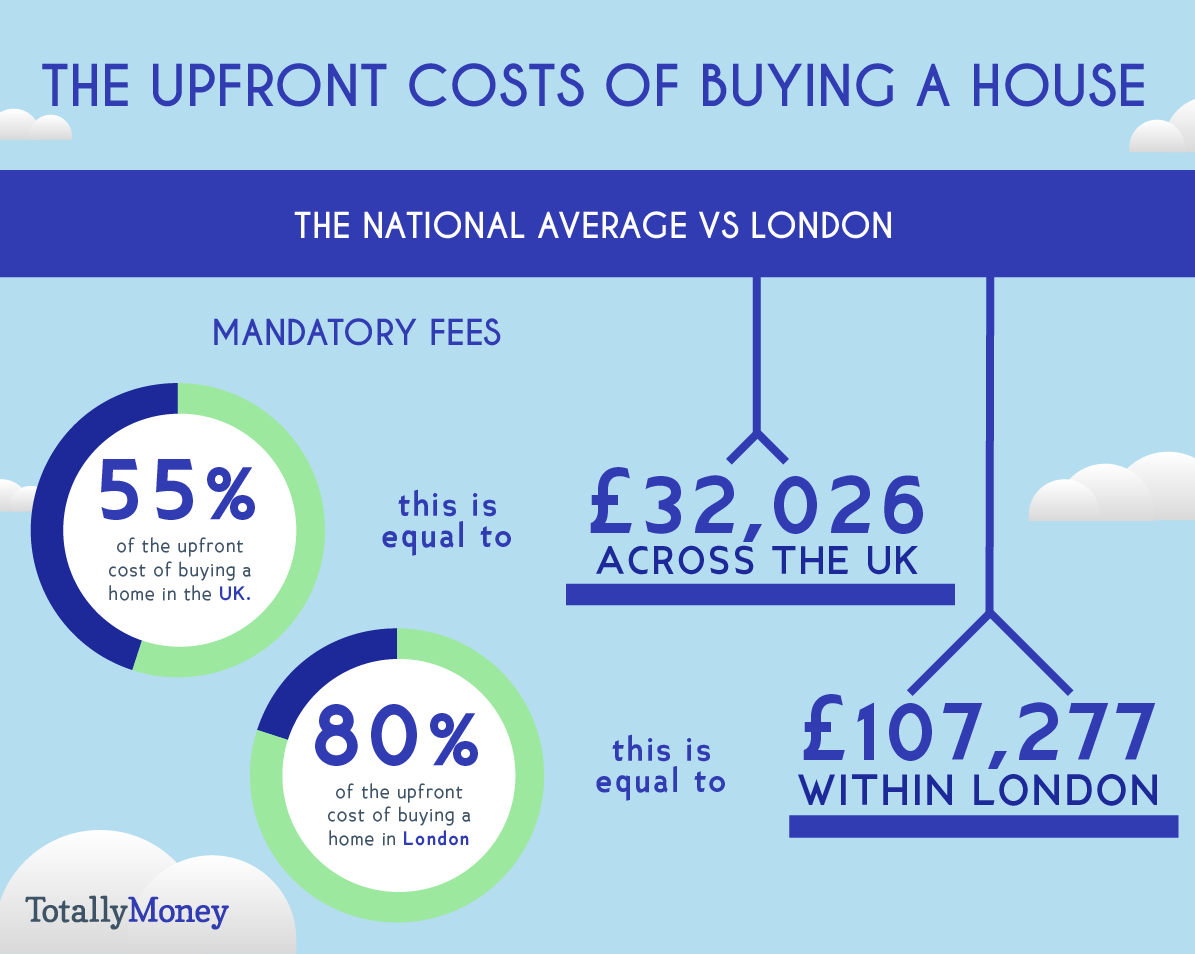
Most first-time buyers obsess over the 5% or 10% deposit. Cute. That’s just the opening act. The real horror show comes from the supporting cast: solicitor fees, survey costs, valuation fees, and mortgage arrangement fees. It’s like buying a ticket to Glastonbury only to discover you also need to pay for the tent, the food, and the emergency poncho.
Must Read
- Did Kelly Clarkson Just Get Julia Roberts Treatment? The Untold Truth Behind Brooklyn’s $15m Animatronic Bird Drama
- The 5-minute Visit That Broke The Internet: How Kelly Clarkson Sparked A $15 Million Mechanical Bird War
- Petty Revenge Or Viral Genius? Brooklyn Store Slaps $15,000,000 Tag On Molly The Bird After Kelly Clarkson Backlash
A decent cost of buying a house UK calculator will itemise these for you. It’ll spit out that your £200,000 starter flat actually needs £12,000 in cash upfront, not just the £10,000 you saved. A cultural touchpoint here: in the UK, we love a queue. This is the financial queue you didn’t know you were standing in.
Fun fact: In 2023, the average first-time buyer spent over £36,000 on total purchase costs. That’s roughly the same as a brand-new Mini Cooper—except the Mini doesn’t leak or need a new boiler.
Stamp Duty: The Tax That Haunts Your Dreams
If you’ve never heard of Stamp Duty Land Tax, buckle up. It’s the government’s way of saying, “Congratulations on your new home—now pay us a fat wedge.” For a £300,000 house, you’re looking at £5,000 just for the privilege. A good calculator lets you plug in your exact price band and see the damage before you fall in love.
Here’s a pro tip: if you’re a first-time buyer on a property up to £425,000, you pay zero stamp duty. That’s right—zero. It’s the closest the taxman gets to offering you a free biscuit with your tea. Make sure your calculator reflects the current relief, or you’ll mourn a phantom cost.
Also, keep an eye on the market. The threshold changes more often than British weather. One minute you’re exempt, the next you’re £2,000 in the hole. The calculator is your weather radar.
Hidden Costs That Sound Fake But Aren’t
Let’s talk about the sneaky stuff. Survey fees—a Level 2 survey can cost £400, a Level 3 (the full works) can hit £1,000. You might skip it, but then you discover the roof is held together with hope and duct tape. The calculator won’t judge you, but your future self will.

Then there’s mortgage arrangement fees, often around £1,000. Some lenders hide them in the interest rate, but your calculator should flag them. And don’t forget buildings insurance—legally required from exchange day. That’s another £200-£400 a year. It’s death by a thousand paper cuts.
Fun fact: The word “mortgage” comes from the Old French “mort gaige,” meaning “death pledge.” Charming, right? It’s because the debt dies when the property is paid off—or when you do. Cheery stuff.
Moving Day: The Final Boss
You’ve crunched the numbers, got the keys, and now you need to actually move your life into a box. Movers cost £500-£1,000 unless you bribe friends with pizza. A quick tip: your calculator should include a line for removals and furniture. You’ll also need a new kettle, because the old one is “energy inefficient.”
Budget for redecorating too. That magnolia wall in the estate agent photos? It’s not a style, it’s a cry for help. A tin of paint costs £30, a decorator costs £300. The calculator reminds you that a house is a money pit dressed up as a sanctuary.
One more hidden gem: ground rent and service charges for leasehold flats. That’s a recurring cost, not a one-off. Some calculators miss this, so find one that doesn’t. Otherwise you’ll be paying for the concierge’s Christmas party every year.
How to Use the Calculator Like a Pro
Don’t just throw in one number. Play God with your finances. Try a £250,000 house, then a £300,000 one. See how the costs swell. It’s like a video game where you lose money instead of lives. Change the deposit percentage from 5% to 10% and watch the monthly mortgage payment shrink—it’s oddly satisfying.
Always run the numbers with a fixed-rate mortgage for two or five years. The calculator shows your monthly outgoings, but also the total cost over the term. That’s where the real shocker lives. A £1,200 monthly payment sounds fine until you see it adds up to £360,000 over 25 years.
Pro tip: Use a calculator that factors in rising interest rates. The Bank of England base rate has a habit of ruining parties. A 2% rate hike can add £300 to your monthly bill. That’s your Netflix, coffee, and takeaway budget, gone.
Cultural Footnotes for the Aspiring Homeowner
Remember that episode of Friends where Monica becomes obsessed with the perfect apartment? That’s you, but with spreadsheets and a soggy Yorkshire. In the UK, we measure success by square footage proximity to a Waitrose. The calculator helps you afford the Waitrose.
Also, Brits love a good rule of thumb: aim for a mortgage no more than 4.5 times your annual salary. If you earn £40,000, that’s a £180,000 mortgage. A calculator will cross-check this and call you out if you’re dreaming beyond your means. It’s the friend who says, “You’re not wearing that, are you?”
And here’s a fun little fact: the average UK house price hit £285,000 in 2024. But that masks huge regional differences. In Yorkshire, you get a terrace house with a garden. In London, you get a parking space with a view of a bin. A good calculator lets you adjust your location, so you don’t cry over postcode envy.
Reflection: The Morning After the Calculator
When you finally close the calculator app, you’ll feel either elated or slightly nauseous. That’s normal. The cost of buying a house in the UK is a terrifying cocktail of hope, tax, and legal jargon. But here’s the truth: every homeowner started exactly where you are, calculator in hand, questioning their life choices.
The reflection that connects to daily life is this: a house is not a destination, it’s a vehicle. It gives you a garden to grow tomatoes, a spare room for your mum, and a kitchen where you can burn toast without judgment. The calculator is just the map. The journey—the late-night talks about paint colours, the joy of a fixed-rate deal, the smugness of fitting a new smart meter—that’s the good stuff.
So open that calculator. Run the numbers. Drink the tea. And remember: homeownership is 10% financial planning and 90% deciding whether to buy a toast rack. You’ve got this.